Money across borders, explained plainly.

Guides for companies that earn, hold and pay in more than one currency: what each payment rail costs, how verification works, how to pay people abroad, and where stablecoins fit.

All articles, page 8

Every guide by country and topic
A bank-to-bank payment that arrives in minutes, with no purchase protection.Payments

Can you use Zelle for business? Limits, fees and the risks

Many US banks let business checking accounts send and receive Zelle. Zelle itself charges no fee, and your bank sets the limits. Payments arrive in minutes and cannot be reversed, and there is no purchase protection, so it suits trusted customers and small amounts.

Rashidatou K.
2 min read
A checklist of US filings for a foreign-owned LLC.Accounts

Opening a US business bank account without an SSN

Non-resident founders are told they need an SSN to bank in the US. For a company account, that is usually wrong. Here is what providers really ask for.

Rashidatou K.
2 min read
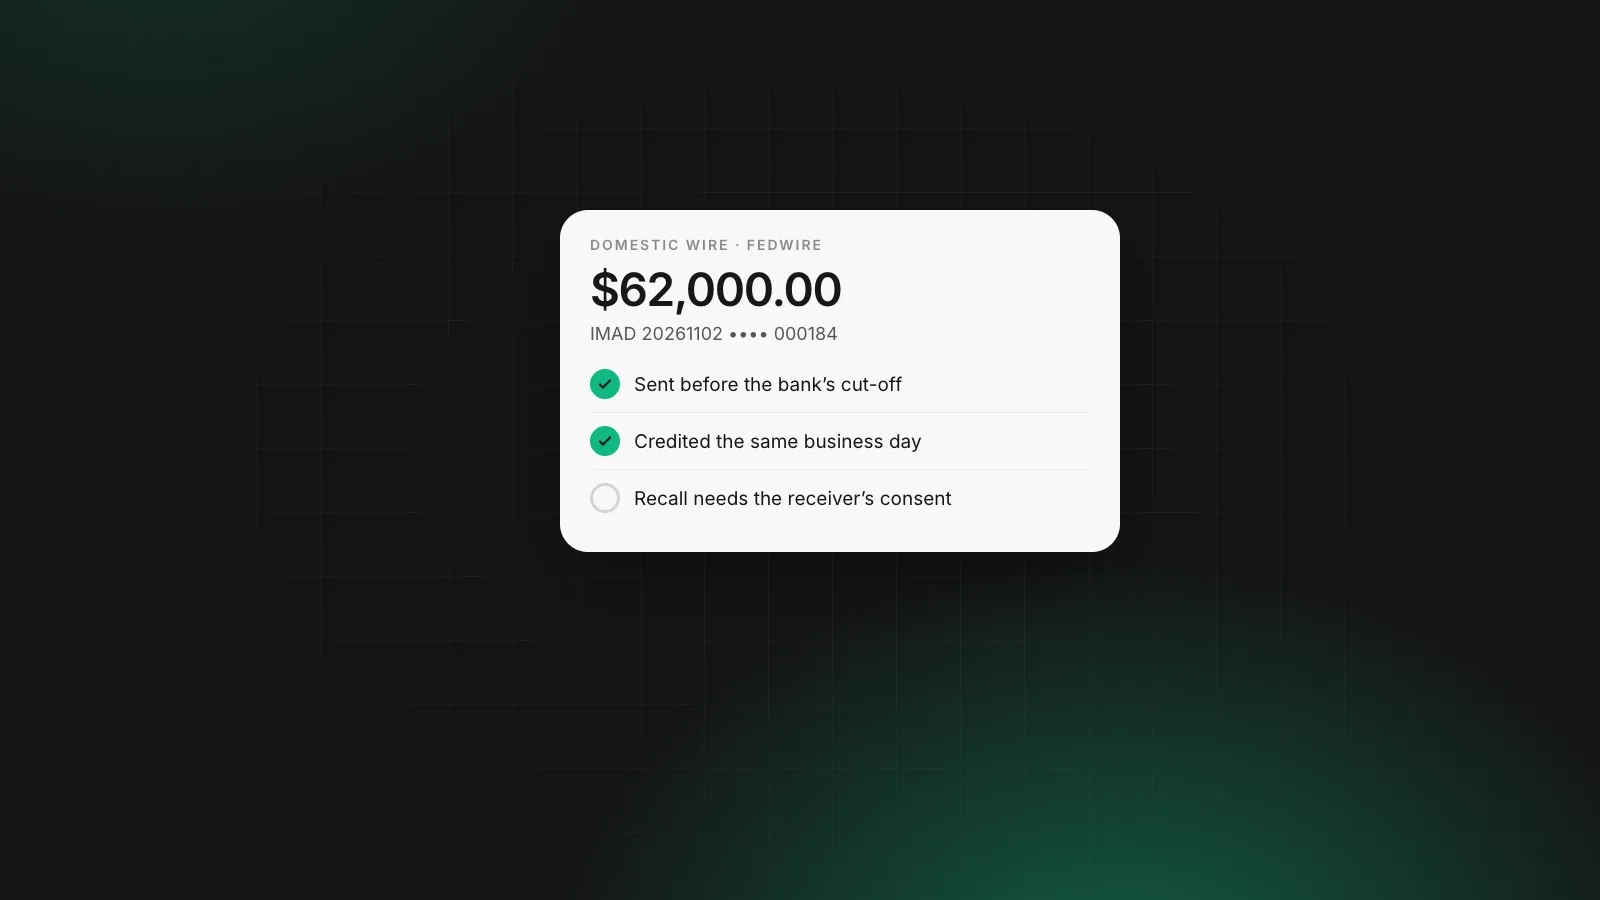
A Fedwire domestic transfer sent before the bank's cut-off with its IMAD reference.Payments

Wire transfer cut-off times in the US: Fedwire hours and bank deadlines

A US domestic wire settles in real time, but only while Fedwire is open and only if your bank sends it before its own cut-off. Fedwire takes customer transfers until 6:00 p.m. Eastern on business days. Most banks set their deadlines hours earlier.

Rashidatou K.
2 min read
A remote team member in India receiving a payment notification.Payments

Paying in India: NEFT, RTGS, IMPS, UPI and Indian rupee payouts

India has some of the fastest domestic payment rails in the world, and some of the most paperwork around money coming in from abroad. Here is what a company paying Indian contractors or suppliers needs to know.

Rashidatou K.
2 min read
A compliance checklist: tax ID, e-invoices, expenses backed by valid invoices and annual return.Compliance

KRA eTIMS in 2026: no eTIMS invoice, no expense deduction?

Every business in Kenya must issue invoices through eTIMS, VAT registered or not. From 1 January 2026, KRA validates the income and expenses in tax returns against eTIMS and other records. An expense without a valid electronic invoice, outside the exempt categories, risks being disallowed.

William Sunjo M.
2 min read
A Ghanaian cedi balance next to a USD balance, with GhIPSS and mobile money rails.Accounts

GHS payments for business: GhIPSS, mobile money and paying in Ghana

Inside Ghana, cedis move by GhIPSS Instant Pay in seconds, by ACH in batches, by RTGS for large sums, and by mobile money, which is linked to bank accounts through interoperability. A foreign company paying Ghana usually sends USD by SWIFT or pays cedis through a provider.

Rashidatou K.
2 min read
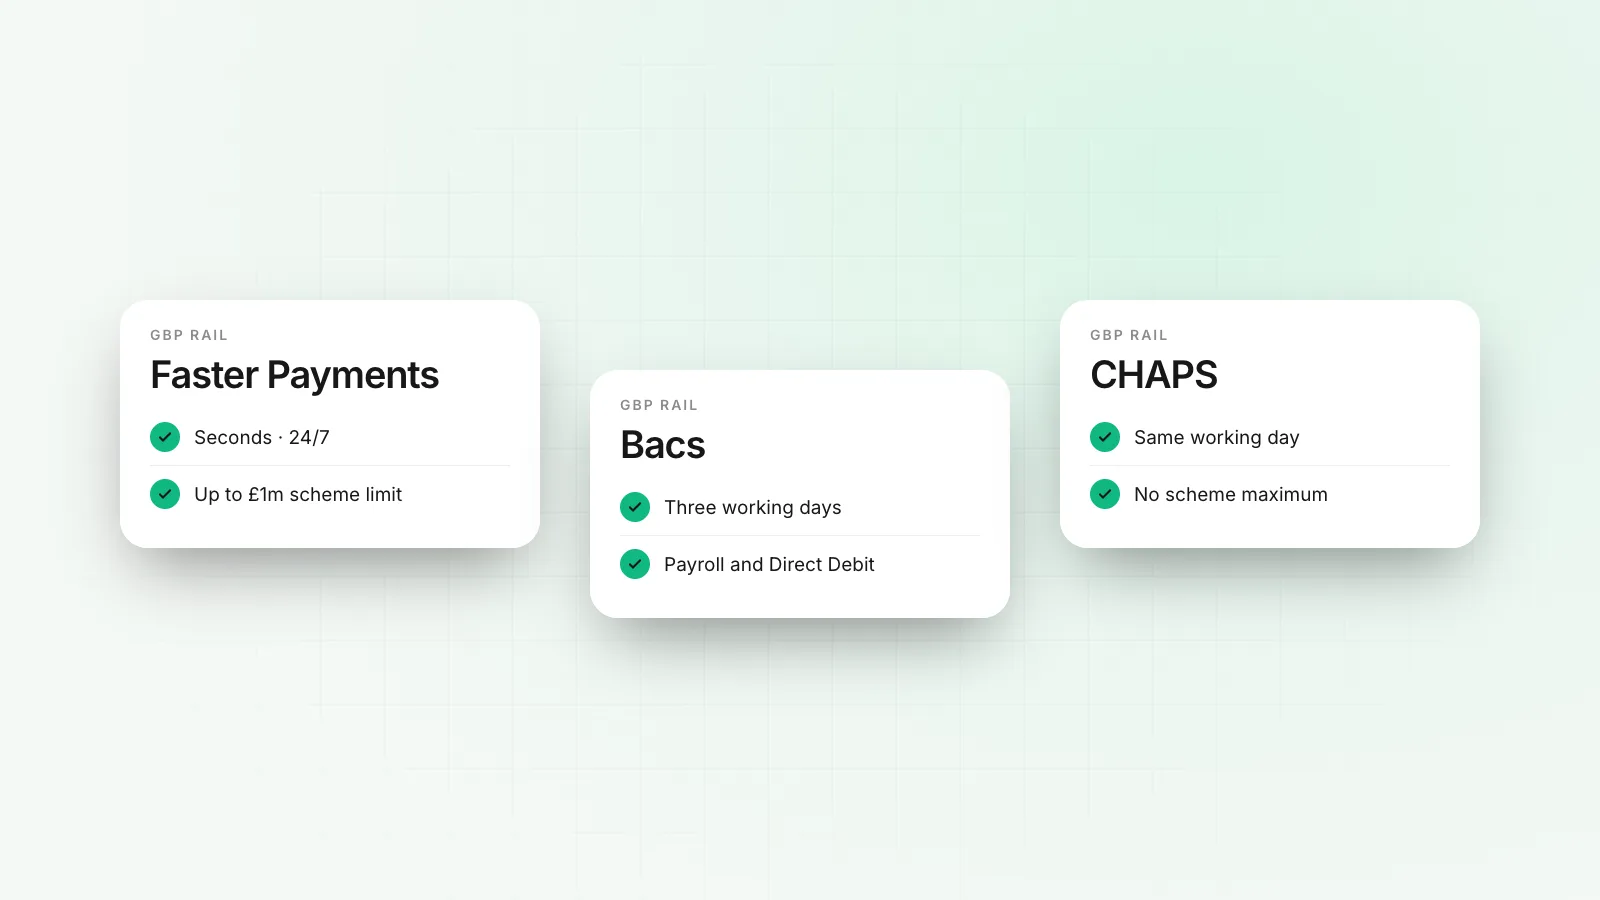
Faster Payments, Bacs and CHAPS compared by speed and limit.Payments

What is the Faster Payments limit in the UK?

Faster Payments can carry up to £1 million per payment. That is the scheme maximum, not your limit. Banks set their own caps by account type and channel, often far lower, and can hold a payment for checks. For larger sums, CHAPS has no scheme maximum.

Rashidatou K.
2 min read

A UK limited company record with its director verified and GBP account details.Operations

Salary vs dividends for UK company directors in 2026/27

Most owner-directors of small UK companies take a small salary and the rest as dividends. The 2026/27 tax year changed the maths: dividend tax rose by two points, and employer National Insurance has started at £5,000 since April 2025.

William Sunjo M.
3 min read
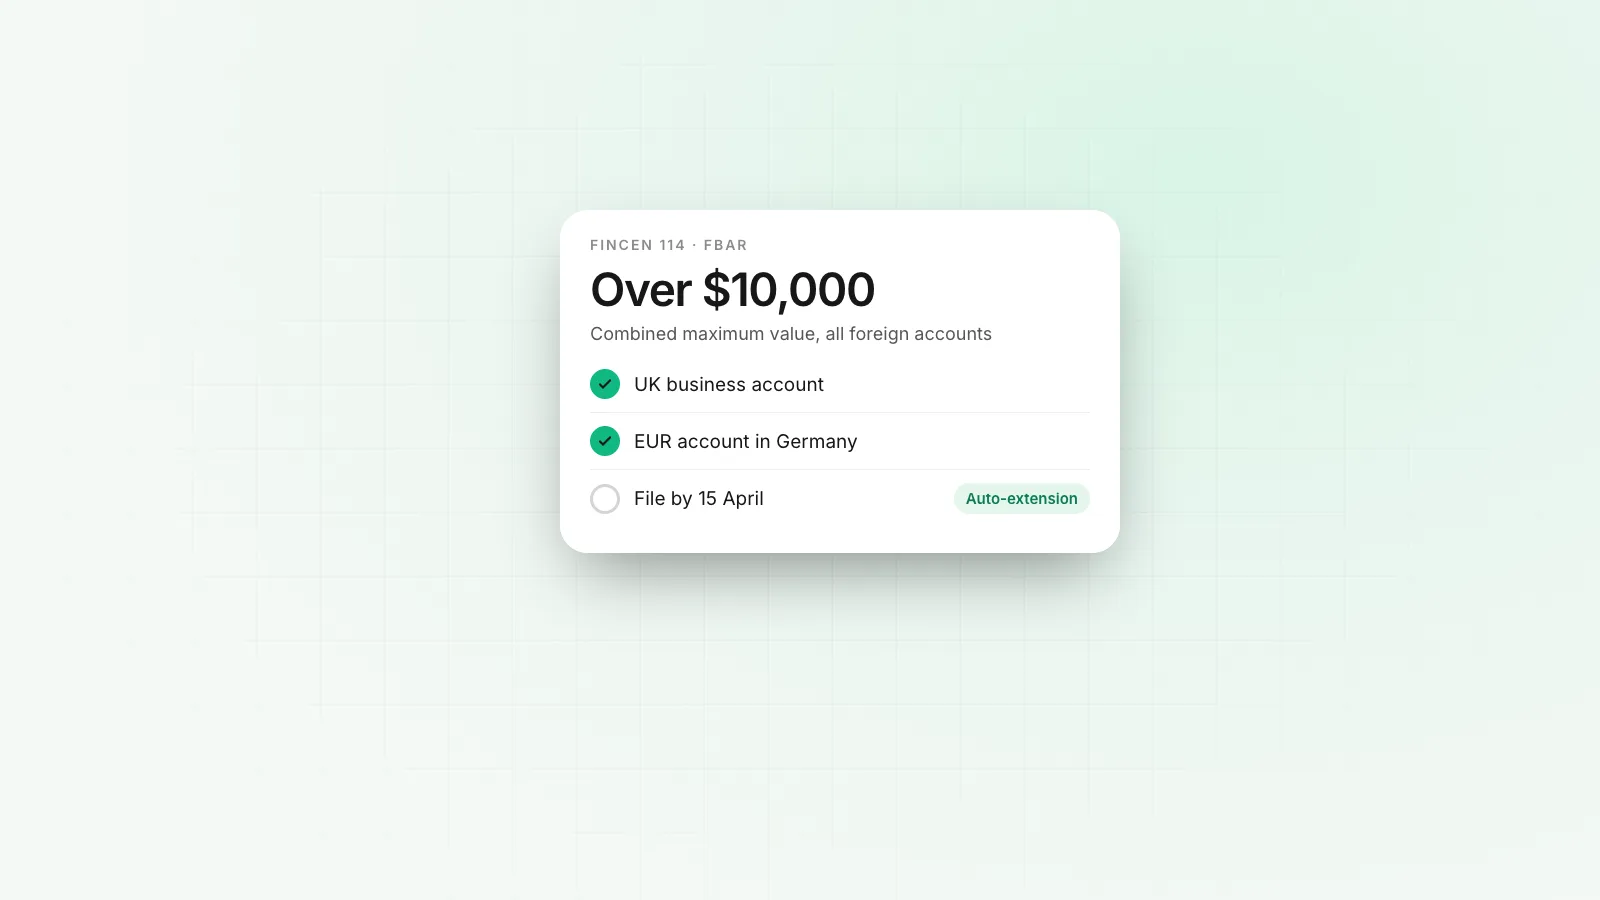
An FBAR checklist for foreign accounts with a combined value over $10,000.Compliance

FBAR explained: who files FinCEN 114, and does your company have to?

If a US person, including a US company, has foreign financial accounts whose combined maximum value went over $10,000 at any point in the year, it must file FinCEN Form 114. A US LLC owned by a non-resident counts as a US person for this purpose.

William Sunjo M.
2 min read
A Confirmation of Payee close match warning before a UK payment.Compliance

Are businesses covered by APP fraud reimbursement in the UK?

Since 7 October 2024, UK payment firms must reimburse victims of authorised push payment scams up to £85,000. The rules cover consumers, microenterprises and small charities. A company with ten or more staff, or larger turnover, is outside them.

William Sunjo M.
3 min read
Who writes here

Written by people who check the source.

Every article is researched against primary sources: the regulation, the scheme rulebook or the provider’s own documentation. Each one lists them at the end.

Subscribe via RSS
Comparisons and market guides editor

Alexia compares the accounts, cards and payment tools companies weigh before they switch, and writes Rivet's market guides for founders in a specific country. Prices in Alexia's comparisons come from each provider's own pricing page on the date given in the article, rules come from the regulator or tax authority that sets them, and every source is listed at the end.

  • Provider comparisons
  • Business banking
  • International payments
  • Market guides
  • Tax and invoicing rules
8 articles
Payments editor

Rashidatou writes Rivet's guides to how money moves between countries: the payment rails, what each one costs, and the account details a company needs to get paid in another currency. Every figure in Rashidatou's articles is traced to the scheme rulebook, the regulator or the provider's published price list, and those sources are listed at the end.

  • Cross-border payments
  • SWIFT and SEPA
  • ACH and wires
  • Multi-currency accounts
  • Stablecoins
88 articles
Operations and compliance editor

William covers what happens once a company starts moving money: getting the business verified, paying contractors and suppliers abroad, and keeping card spend under control. William writes for the founder or finance lead who has to make it work this week, and links every rule cited to the text it comes from.

  • Business verification (KYB)
  • Contractor payouts
  • Corporate cards
  • Ad spend
  • Finance operations
90 articles
Rivet

One business account for every currency you earn in.

Bank accounts in USD, EUR and GBP, cards with a limit on each, and payouts on local rails. Starter is free.

New rules, rail changes and fee moves in one short email. Unsubscribe any time. Privacy notice

Global

USD, EUR, GBP and 22 more currencies in the account. Payouts go to 120+ countries on the local rail.

Any hour

You can convert currencies and settle on-chain at any hour, including when banks are closed.

Rivet is a financial technology platform, not a bank. Regulated partner institutions provide the accounts, payment services and cards, under their own terms and eligibility rules. Those institutions hold and move the funds. The money is not pooled on our balance sheet.

The names and logos of Amazon, Meta, Visa, Google Play, App Store, Swift, SEPA, Faster Payments, Circle, Tether and others are trademarks of their owners. We show them so you can tell which network a payment settles on. Rivet is not affiliated with, endorsed by, or sponsored by these companies. Digital assets are not deposits, are not legal tender, and may lose value. Products and services are not available in all jurisdictions.

Money transmission services are provided by Bivo Inc. (NMLS 2572288).

© 2026 Bilitech LLC. All rights reserved.Bilitech LLC · 30 N Gould St Ste N, Sheridan, WY 82801