FBAR explained: who files FinCEN 114, and does your company have to?
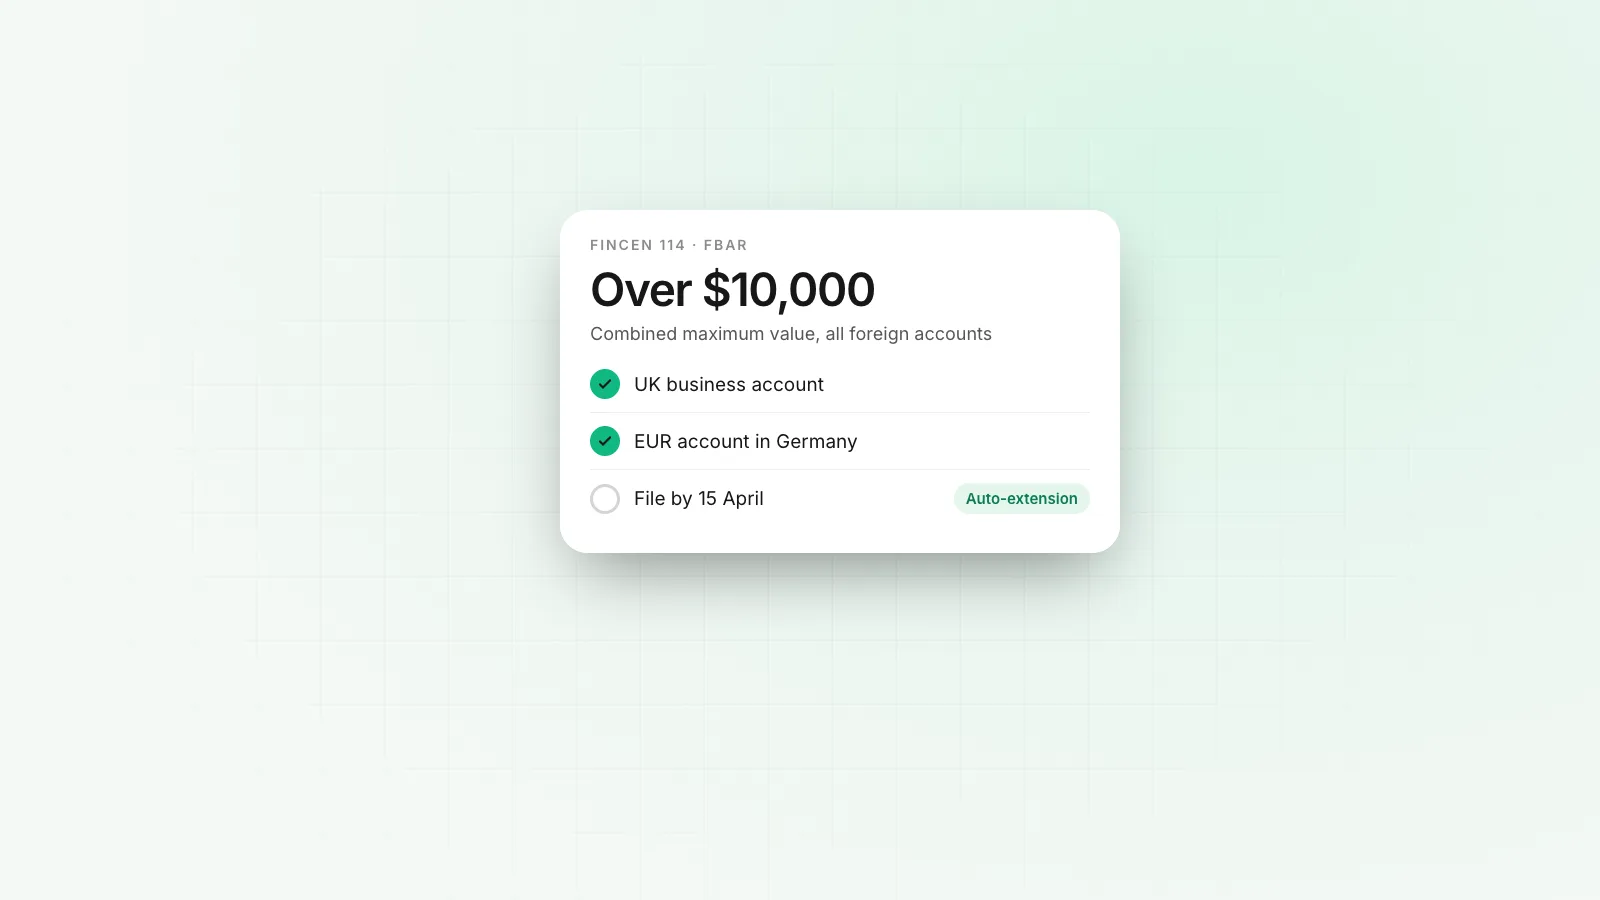
If a US person, including a US company, has foreign financial accounts whose combined maximum value went over $10,000 at any point in the year, it must file FinCEN Form 114. A US LLC owned by a non-resident counts as a US person for this purpose.
- Published
- Reading time
- 2 min read
The FBAR is one of the easiest US filings to miss, because it has nothing to do with income. It reports foreign accounts. Individuals living abroad know it well. Companies, especially US LLCs owned by people outside the US, often find out about it late.
What is an FBAR?
FBAR stands for Report of Foreign Bank and Financial Accounts. It is filed on FinCEN Form 114 with the Financial Crimes Enforcement Network, part of the US Treasury. It tells the government which foreign financial accounts a US person had, and the highest value of each during the year. It does not calculate any tax.
Who has to file?
A US person who had a financial interest in, or signature authority over, foreign financial accounts whose combined maximum value exceeded $10,000 at any time during the calendar year.
US persons include:
- US citizens and residents, wherever they live.
- Corporations, partnerships and LLCs formed in the US.
- Trusts and estates formed in the US.
That second point catches many founders. A Wyoming or Delaware LLC owned entirely by a non-resident is a US entity. If the LLC holds an account at a bank or payment provider outside the US, and the combined maximum went over $10,000, the LLC files an FBAR.
What counts as a foreign financial account?
| Counts | Does not count |
|---|---|
| Bank accounts at foreign banks | Accounts at US banks, even if they hold foreign currency |
| Accounts at foreign payment providers and e-money institutions | US branches of foreign banks |
| Foreign securities and brokerage accounts | Accounts held only through a US custodian |
| Foreign mutual funds |
Location of the institution is what matters. A EUR account held with a US provider is not foreign. A GBP account at a UK bank is.
How is the $10,000 calculated?
Take the highest balance each account reached during the year, convert each to US dollars at the Treasury's year-end exchange rate, and add them up. If the total exceeds $10,000, you file and list every account, including those that were small.
When is it due?
15 April following the calendar year, with an automatic extension to 15 October. You do not need to request the extension. It is filed electronically through FinCEN's BSA E-Filing System, separately from the tax return.
What are the penalties?
Penalties for non-wilful failure to file can run to more than $10,000 per violation, adjusted for inflation. In Bittner v. United States (2023), the Supreme Court held that the non-wilful penalty applies per report, not per account, which limits exposure for people who missed a year with many accounts. Wilful violations carry much higher penalties. If you have missed FBARs, the IRS has procedures for late filing with reasonable cause.
What about Form 5472 and other filings?
A foreign-owned single-member LLC also files Form 5472 every year. The FBAR is in addition, not instead. See the Form 5472 guide and BOI reporting after 2025.
Where Rivet accounts sit
Whether an account counts as foreign depends on where the institution holding it is located, so check with your tax adviser for your exact setup. Rivet gives registered companies, including non-resident-owned US LLCs, USD account details in the company's name, and the account statements show the maximum balance figures an adviser needs for the year.
Questions people ask
Does a foreign-owned US LLC have to file an FBAR?
If the LLC itself has foreign financial accounts whose combined maximum value exceeded $10,000 during the year, yes. The LLC is a US entity and so a US person for FBAR purposes, even though its owner is not.
Is the $10,000 threshold per account?
No. It is the total of the maximum values of all foreign accounts during the year. Two accounts that each peaked at $6,000 trigger the requirement.
Is an FBAR the same as Form 8938?
No. Form 8938 is a FATCA form filed with the tax return, with higher thresholds and different rules. Some taxpayers must file both.
Do accounts at fintech providers count?
If the account is held with a financial institution located outside the US, it generally counts, whether it is a bank or a payment provider. A US-located account does not count, even if it holds foreign currency.
Sources
William covers what happens once a company starts moving money: getting the business verified, paying contractors and suppliers abroad, and keeping card spend under control. William writes for the founder or finance lead who has to make it work this week, and links every rule cited to the text it comes from.
More from William Sunjo M. →This article is general information, not legal, tax or financial advice. Rules and fees change; check the sources above and the provider’s current terms before you act on them.
- fbar
- fincen 114
- foreign bank account
- us llc
- us tax
- reporting