Every rail your
clients already use.[product]What you get
with Rivet
Issued to your entity
in USD, EUR, GBP and 24 more
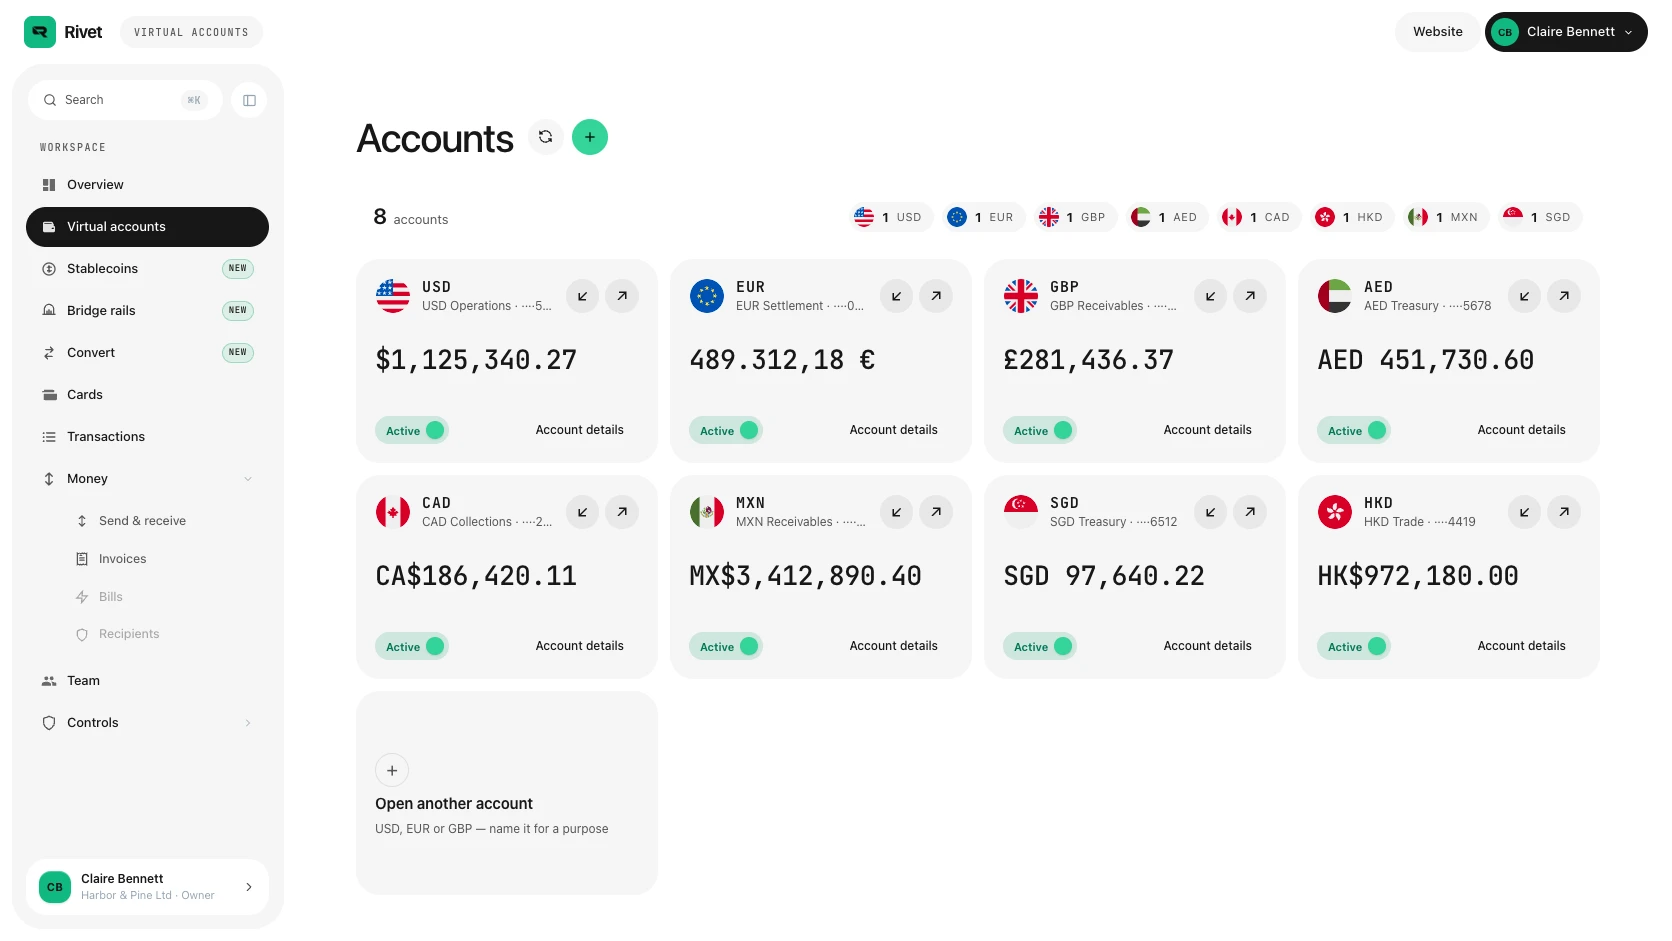
Named accounts across 24+ currencies. One login.
No more juggling three banks and a wallet.
Four things every growing team runs into.
Rivet was built around all four.
One bank, one currency,one rail. Then you landa client abroad.
Opening a euro account means a euro bank. Adding a UK rail means another one. Every new market is a project, and finance ends up with a login per country.
Many rails.One login.
US details with ACH and wires. Euro details with SEPA and SEPA Instant. UK details with Faster Payments. All issued to your entity, all in one account, all in one feed.
Cross-currency movescost real money.
Every conversion has a spread. Some banks hide it in the rate, some add it as a fee. Either way it compounds across a year of invoices.
24+ currencies.Published rates.
Hold what you invoice in and convert only when you choose. The rate and the fee are on screen before you confirm. FX from 0.80% on Starter, falling to 0.15%.
A pooled account witha reference numberis not your account.
Plenty of platforms give you a shared account and a code to put in the payment note. Miss the code and the money sits in limbo. Your client sees a stranger as the payee.
Details in yourcompany name.
Once the entity passes KYB the details are issued to it. A wire, an ACH and a SEPA all show your company as the payee, and each credit lands in the matching balance with its own reference.
Stablecoins and bankingshould not be two stacks.
If the business touches USDC or USDT, it usually juggles a bank, an exchange and a wallet. Three logins, three reconciliations, three places to lose money.
USDC and USDT,in one window.
USDC and USDT sit beside your USD, EUR and GBP, on six networks. Move between fiat and stablecoin from inside the account, 24/7, with the rate shown first.
Get paid onthe local rail
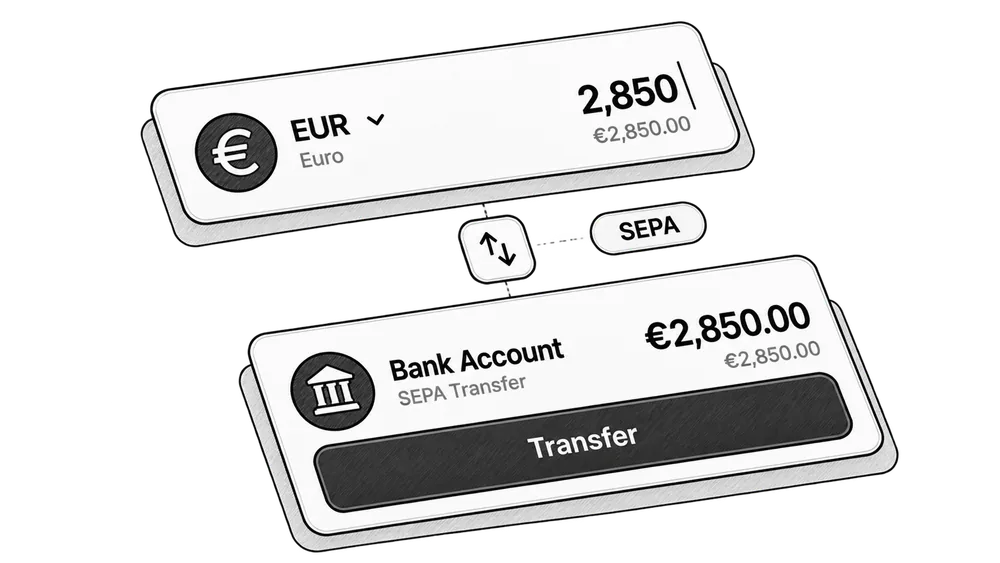
ACH and wires into your USD details, SEPA into your euro details, Faster Payments into your GBP details. A Swift wire from anywhere lands in the same balance. Every credit shows up in the feed as it arrives.
Hold smart,convert when you choose
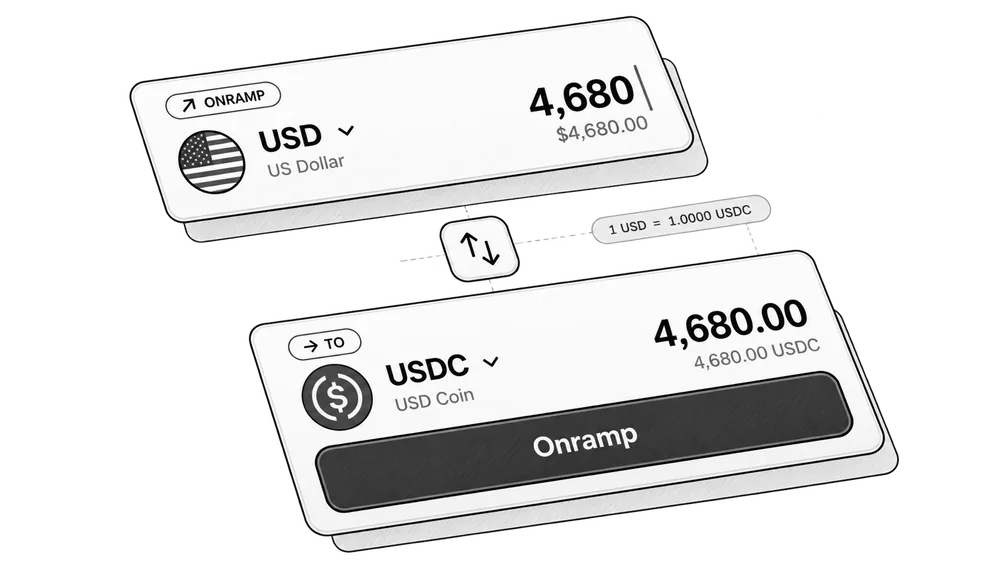
Keep the euro invoice in euros and the dollar invoice in dollars. Convert between 24+ currencies, or into USDC and USDT, with the rate and fee on screen before you confirm.
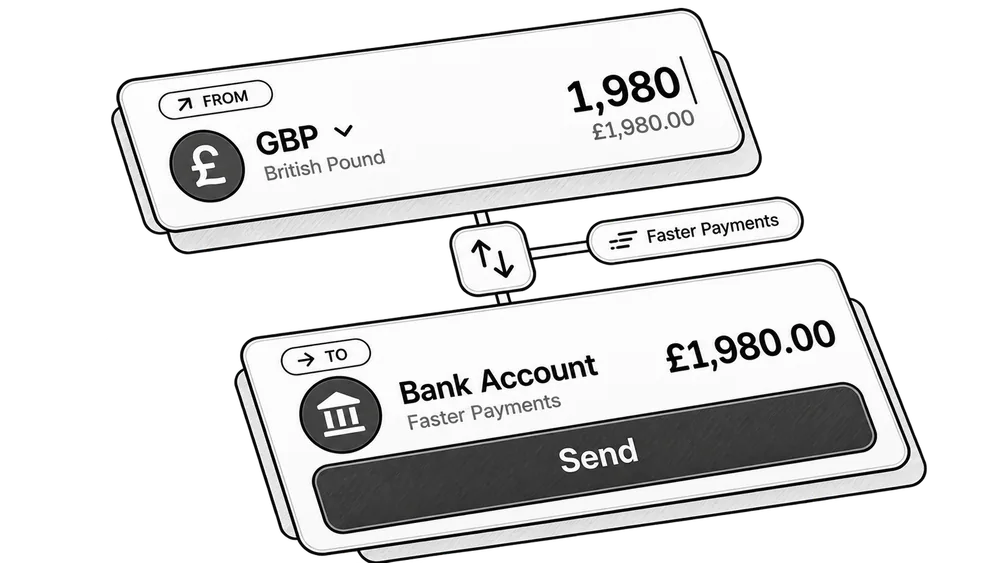
Send anywhere,on the right rail
A card charge, a single transfer or a batch of 46 payouts, each on the rail the recipient already uses. The balance a client paid into is the balance a payout draws on. Nothing is swept to a second provider first.
Money →

 moves differently.
Sub-
accounts
Per client, project or entity.
USD
US dollar
Account number
1234 5678 9012 3456
EUR
Euro
IBAN
DE89 3704 0044 0532 0130 00
GBP
Sterling
Sort · account
20-98-76 54321011
Real‑time
credits
In the feed as each payment lands.
Luma StudioSEPA+€8,750NorthstarACH+$12,481Multi-currency
accounts
USD, EUR and GBP details, 21 more balances, one login.
USD
US dollar
Account number
1234 5678 9012 3456
EUR
Euro
IBAN
DE89 3704 0044 0532 0130 00
GBP
Sterling
Sort · account
20-98-76 54321011
No minimum
balance
$0Nothing parked. Nothing
per account opened.
Card
issuance
 Rivet
James Whitaker
···· 9184
RivetElena Rossi
···· 4821
Digital in seconds,
physical from Growth.
Convert
Hold & convert 24+ currencies. The rate shown first.
Ledger
export
CSVPDFAny period, matched
to your references.
Approval
workflows
A second approver
above your threshold.
Safe by design
No paper. No branches.
A verdict in 0 business days on a complete file.
Yes. Once the entity passes KYB the details are issued to your company, so your client sees your name when they set up the payee. Not a reference number against a pooled account someone else also pays into.
No minimum balance and no maintenance fee on the account itself. There is a monthly plan fee. Starter is free; Growth and Scale are on the pricing page. The plan decides how many currencies you can open, not a balance you have to keep parked.
USD, EUR and GBP are what most businesses open first: an account and routing number for USD, an IBAN for EUR, a sort code for GBP. Scale adds CAD, HKD and 21 more: local details where we issue them, balances you can hold and convert where we do not.
Yes. Create sub-accounts per client, project or entity so incoming funds arrive already separated, rather than being split apart afterwards from one statement.
On the rail the sender used: same day for ACH and domestic wires, minutes to same day for SEPA and SEPA Instant, minutes for Faster Payments. It lands in the matching currency balance, and you see it as it arrives rather than at the end of the day.
Receiving over a local rail (ACH, SEPA or Faster Payments) is what the account is for, and the per-rail fees on the pricing page apply per transfer: SEPA is €5.00 falling to €3.00 on Scale, Faster Payments £3.00 falling to £2.00. A Swift wire is the expensive one at $25.00, falling to $20.00, which is the argument for giving a client local details instead of asking them to wire.
It sits in that currency balance. From there you can hold it, convert between currencies, move it into USDC or USDT, spend it on a card, or pay it out, including as one leg of a bulk batch. There is no separate exchange account in between.