Can you send ACH internationally? IAT and cross-border ACH explained
No, not in the way most people hope. ACH moves money between US accounts. An IAT entry is used when an ACH payment involves money moving to or from a bank outside the US, but it only reaches a handful of countries. To pay most suppliers abroad, you need SWIFT or a local payout.
- Published
- Reading time
- 2 min read
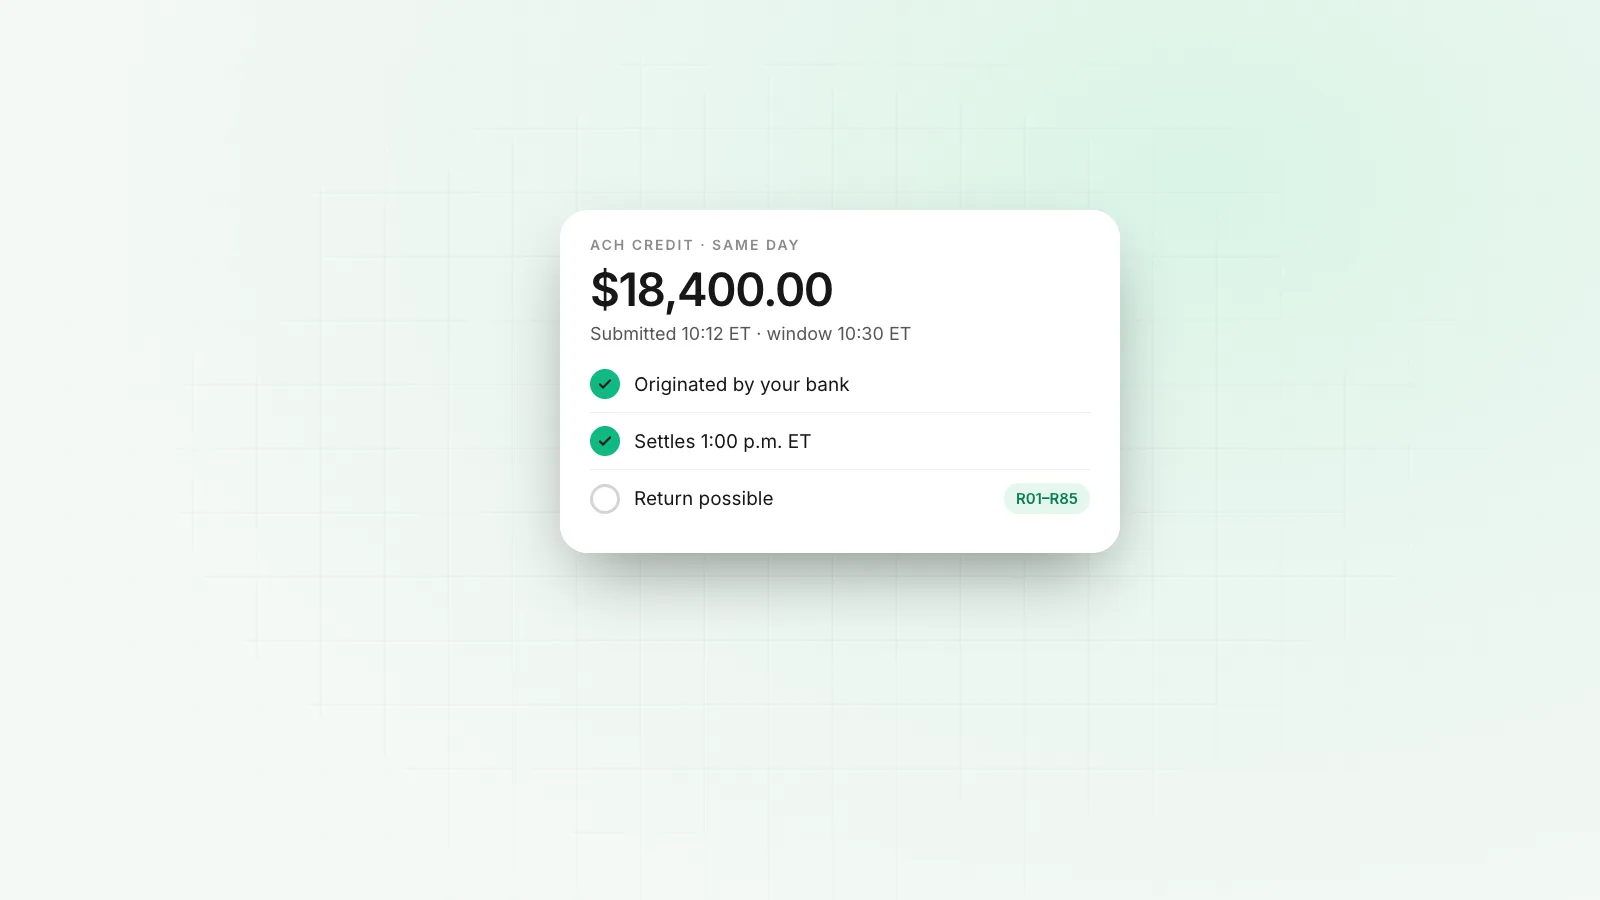
ACH is cheap and familiar, so US businesses often ask whether they can use it to pay a contractor in the Philippines or a supplier in Germany. The short answer is no for most countries. ACH is built around US bank accounts. Here is where it does cross borders, and what to use instead.
What is an IAT entry?
IAT stands for International ACH Transaction. Nacha, which writes the rules for the ACH Network, requires the IAT code on any ACH entry that is part of a payment moving money to or from a financial agency outside the US. It was introduced in 2009 so that cross-border payments carry the information US sanctions screening needs.
An IAT entry carries more data than a domestic one:
- The names and addresses of the originator and the receiver.
- The originating and receiving banks, and their countries.
- The reason for payment, in some cases.
Banks screen IAT entries against OFAC sanctions lists, which can delay them.
Can you send ACH to a foreign bank?
Only to a few countries, and only if your bank supports it. The Federal Reserve's FedGlobal ACH service connects to a limited set of countries through partner banks. Some US banks offer cross-border ACH through their own arrangements. For the rest of the world, ACH does not reach.
When does a domestic ACH need the IAT code?
Sometimes a payment that looks domestic has to be coded IAT. If a US payment provider takes an ACH debit from your account to fund a payment that it then sends abroad, the ACH leg may need the IAT code because the funds are part of a cross-border flow. Your bank or provider decides this, but it explains why some payments show "IAT" and take longer.
What do businesses use instead?
| Option | How it works | Typical cost | Speed |
|---|---|---|---|
| SWIFT wire | Your bank sends USD or converts, through correspondent banks | $25 to $50 sending fee, plus correspondent and receiving fees | 1 to 5 business days |
| Local payout through a provider | The provider pays the recipient on their country's domestic rail | Lower per-payment fee, plus FX margin | Same day to 2 days |
| Stablecoin transfer | USDC or USDT sent to the recipient's wallet | Network fee | Minutes |
For a supplier invoiced in USD, a SWIFT wire may be fine. For contractors paid in local currency every month, local payouts avoid the deductions that make SWIFT unpredictable. See SWIFT transfer fees and time and how to pay international contractors.
What about receiving from abroad?
The reverse problem is common too. A foreign client cannot pay your US ACH details unless it has a US bank account. Most foreign clients send a SWIFT wire to your wire routing number, or pay into local details in their own currency if you have them. See how to receive international payments.
Paying abroad from a Rivet account
Rivet gives registered companies USD account details for ACH and wires, and on Growth, payouts to 120+ countries. A batch of international payouts goes to each recipient on their local rail where we support it, with the fee and exchange rate shown before you approve, so a contractor in Mexico gets pesos by SPEI and a supplier in Germany gets euros by SEPA.
Questions people ask
What does IAT mean in ACH?
International ACH Transaction. It is the Standard Entry Class code required when an ACH entry is part of a payment that moves funds to or from a financial agency outside the US.
Can I send an ACH to a Canadian or Mexican bank?
Some US banks can, through FedGlobal ACH or arrangements with foreign banks, and the payment is sent as an IAT entry. Many banks do not offer it, so ask yours.
Why was my payment marked IAT when both accounts are in the US?
If the money is funded from or going on to an account outside the US, for example through a payment provider, Nacha rules can require the IAT code even if the ACH leg itself is domestic.
What is the cheapest way to pay a supplier abroad from the US?
For regular payments, a local payout in the supplier's currency is usually cheaper than a SWIFT wire, because it avoids correspondent fees and the receiving bank's charges. Compare the FX rate as well as the fee.
Sources
Rashidatou writes Rivet's guides to how money moves between countries: the payment rails, what each one costs, and the account details a company needs to get paid in another currency. Every figure in Rashidatou's articles is traced to the scheme rulebook, the regulator or the provider's published price list, and those sources are listed at the end.
More from Rashidatou K. →This article is general information, not legal, tax or financial advice. Rules and fees change; check the sources above and the provider’s current terms before you act on them.
- international ach
- iat
- cross-border payments
- ach
- international payouts
- usd