Wire transfer vs Zelle for business payments
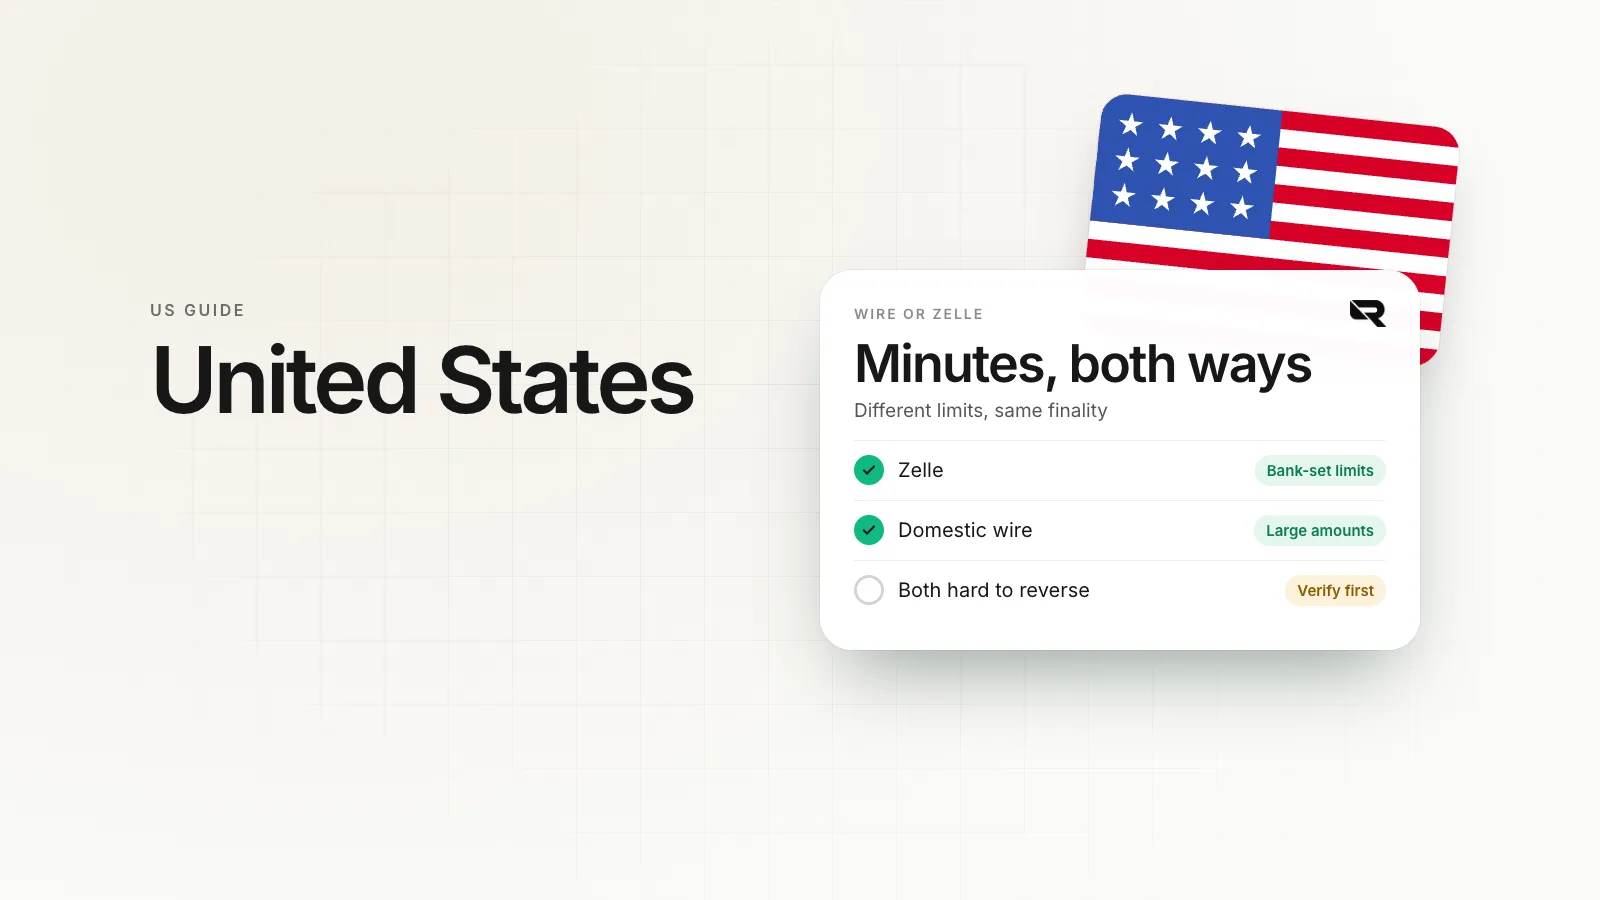
Zelle moves small amounts between US bank accounts in minutes, with bank-set limits. Wires move large amounts with full details. Both are hard to reverse, so both need care.
- Published
- Reading time
- 1 min read
Google completes "wire transfer vs" with "ach", "zelle" and "cashier check". For businesses, the Zelle comparison is about limits and risk.
Side by side
| Zelle | Domestic wire | |
|---|---|---|
| Speed | Minutes | Same day |
| Limits | Set by your bank; often low | High |
| Cost | Usually free | Fee at many banks |
| Reversal | Very hard | Very hard |
| Details needed | Email or phone number | Full account and routing |
| International | No | Domestic only (international is a different wire) |
When Zelle fits
Paying a local contractor a few hundred dollars, or receiving a small payment from a customer who banks in the US. See Zelle for business.
When a wire fits
A large, time-sensitive payment, such as a property deposit or a supplier who will not ship until paid.
The fraud angle
Both are favourite targets for fraud because they are fast and final. Confirm new payee details by phone using a number you already have, not one in the email.
Paying into the United States: the local rail
| What | Detail |
|---|---|
| Local rail | ACH for batch payments; RTP and FedNow for instant transfers |
| Run by | Nacha for ACH; The Clearing House for RTP; the Federal Reserve for FedNow |
| Settlement | Same-day ACH within the business day, standard ACH the next; RTP and FedNow in seconds, 24/7, where both banks take part |
Source: Nacha: Same Day ACH. Checked when this guide was last updated; the scheme's own page has the current figures.
Where Rivet fits
Rivet sends payouts by ACH and wire in the US and on local rails in 120+ countries, with the payee confirmed and the fee shown before you send. Approvals on Growth let a second person check large payments. Rivet is not a bank; regulated partner institutions hold the funds. See invoice fraud and payment detail scams.
Questions people ask
Is Zelle good for business payments?
For small, occasional payments to people you know, it can be. Limits are low, and Zelle's own terms say to use it only with people you trust.
Can a wire be reversed?
Rarely. Once a wire settles, recovering it depends on the recipient bank's cooperation. See our guide on cancelling a wire.
What about ACH?
ACH is cheaper than a wire, slower than Zelle, and better for regular payments like payroll and suppliers.
How do I pay someone abroad?
By international wire or through a provider that pays out locally in the recipient's country.
Sources
Alexia compares the accounts, cards and payment tools companies weigh before they switch, and writes Rivet's market guides for founders in a specific country. Prices in Alexia's comparisons come from each provider's own pricing page on the date given in the article, rules come from the regulator or tax authority that sets them, and every source is listed at the end.
More from Alexia M. →This article is general information, not legal, tax or financial advice. Rules and fees change; check the sources above and the provider’s current terms before you act on them.
- wire transfer vs zelle
- zelle for business
- wire transfer
- payment fraud
- us business payments