Business check fraud and Positive Pay: how to protect your account
US businesses still lose more to check fraud than to any other payment type. Positive Pay compares every check presented against a list you upload, and stops the ones that do not match. Payee Positive Pay also checks the name, which catches washed checks.
- Published
- Reading time
- 2 min read
Checks are old technology, and fraudsters like them for it. Every check carries your bank's routing number, your account number and your signature. A stolen check can be washed and rewritten, copied onto new stock, or used as a template for counterfeits. For US businesses, check fraud is still the most common kind of payment fraud.
How does business check fraud work?
| Type | How it works |
|---|---|
| Mail theft and washing | A check is stolen in the mail, the ink is removed chemically, and a new payee and amount are written in |
| Counterfeit | New checks are printed with your account details, often from an image of a real one |
| Altered amount | A real check's amount is changed |
| Forged signature | A blank check is stolen and signed |
| Insider fraud | Someone inside writes checks to themselves or a fake vendor |
FinCEN issued an alert in 2023 about a nationwide surge in check fraud linked to mail theft, and the Association for Financial Professionals' annual survey has found checks to be the payment type most often hit by fraud year after year.
What is Positive Pay?
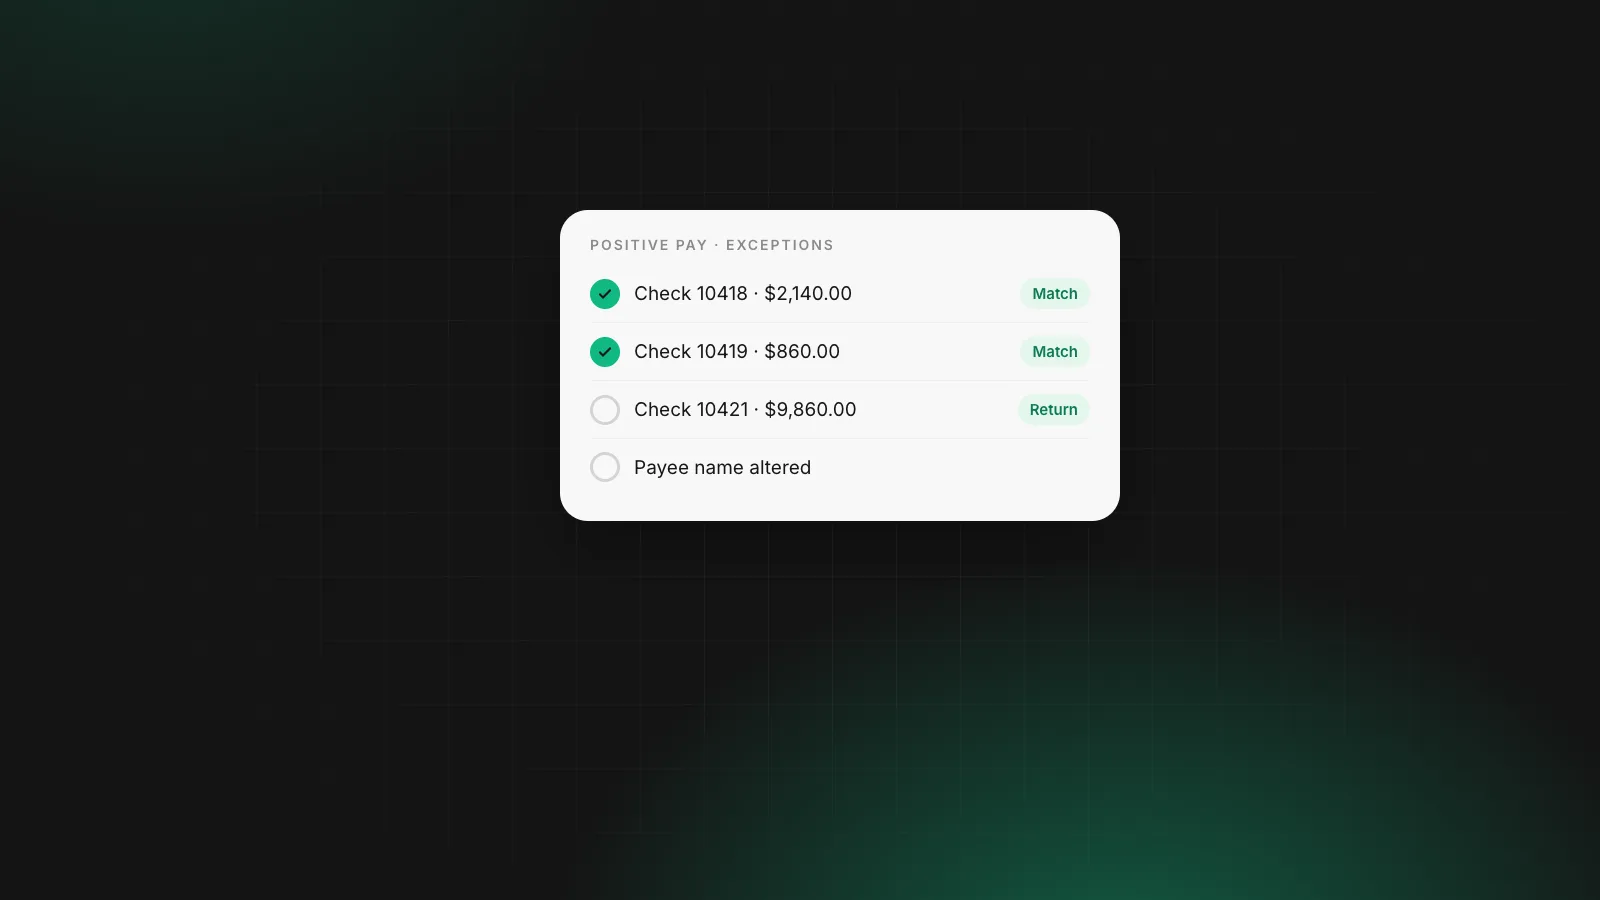
Positive Pay is a service most US business banks offer. Each time you write checks, you send the bank an issue file listing check number, amount and date. When a check is presented for payment, the bank compares it with the file. A check that does not match becomes an exception. You review exceptions, usually through online banking, and tell the bank to pay or return each one before a daily cut-off.
What is Payee Positive Pay?
Standard Positive Pay checks number, amount and date. A washed check often keeps the original amount and number and changes only the payee. Payee Positive Pay adds the payee name to the comparison, which catches that. If your bank offers it, it is worth the extra fee.
How do you set it up?
- Ask your bank for Positive Pay, and Payee Positive Pay if offered.
- Connect your accounting or check-printing software to produce the issue file.
- Send the file each time you issue checks, before they could be presented.
- Choose the default decision for unreviewed exceptions. Return is safer.
- Assign someone to review exceptions every business day, with a backup.
What about ACH fraud?
Fraudsters who get your account details can also try ACH debits. Most banks offer ACH debit block, which refuses all ACH debits, and ACH debit filter, which allows only originators you approve. Turn one on for any account that does not need to be debited by third parties.
Should you stop writing checks?
Many businesses are cutting back. The US Treasury stopped issuing most paper checks for federal payments from 30 September 2025, under a March 2025 executive order. For supplier payments, ACH is cheaper, faster and harder to tamper with. Ask suppliers for their bank details, confirm them by phone, and pay by ACH. See ACH vs wire and ACH debit vs ACH credit.
Paying without checks
Rivet does not issue checks. Registered companies pay US suppliers by ACH or wire from their USD account, and suppliers abroad on local rails in 120+ countries, with roles and approvals from the Growth plan.
Questions people ask
What is Positive Pay?
A bank service where you send the bank a list of checks you have issued. When a check is presented, the bank compares it with the list and holds any mismatch for you to approve or return.
Does Positive Pay catch washed checks?
Standard Positive Pay checks number, amount and date, so a washed check with the original amount can get through. Payee Positive Pay also compares the payee name, which is what changes on a washed check.
How much does Positive Pay cost?
Banks charge a monthly fee, sometimes per item. For a business that writes checks regularly, the fee is usually small next to one fraudulent check.
Who is liable if a fraudulent check is paid?
It depends on the facts and your bank agreement. Many business account agreements shift liability to the customer for checks that Positive Pay would have caught if the business declined the service.
Sources
William covers what happens once a company starts moving money: getting the business verified, paying contractors and suppliers abroad, and keeping card spend under control. William writes for the founder or finance lead who has to make it work this week, and links every rule cited to the text it comes from.
More from William Sunjo M. →This article is general information, not legal, tax or financial advice. Rules and fees change; check the sources above and the provider’s current terms before you act on them.
- check fraud
- positive pay
- payee positive pay
- business banking
- payment fraud
- us