Singapore withholding tax on payments to overseas suppliers
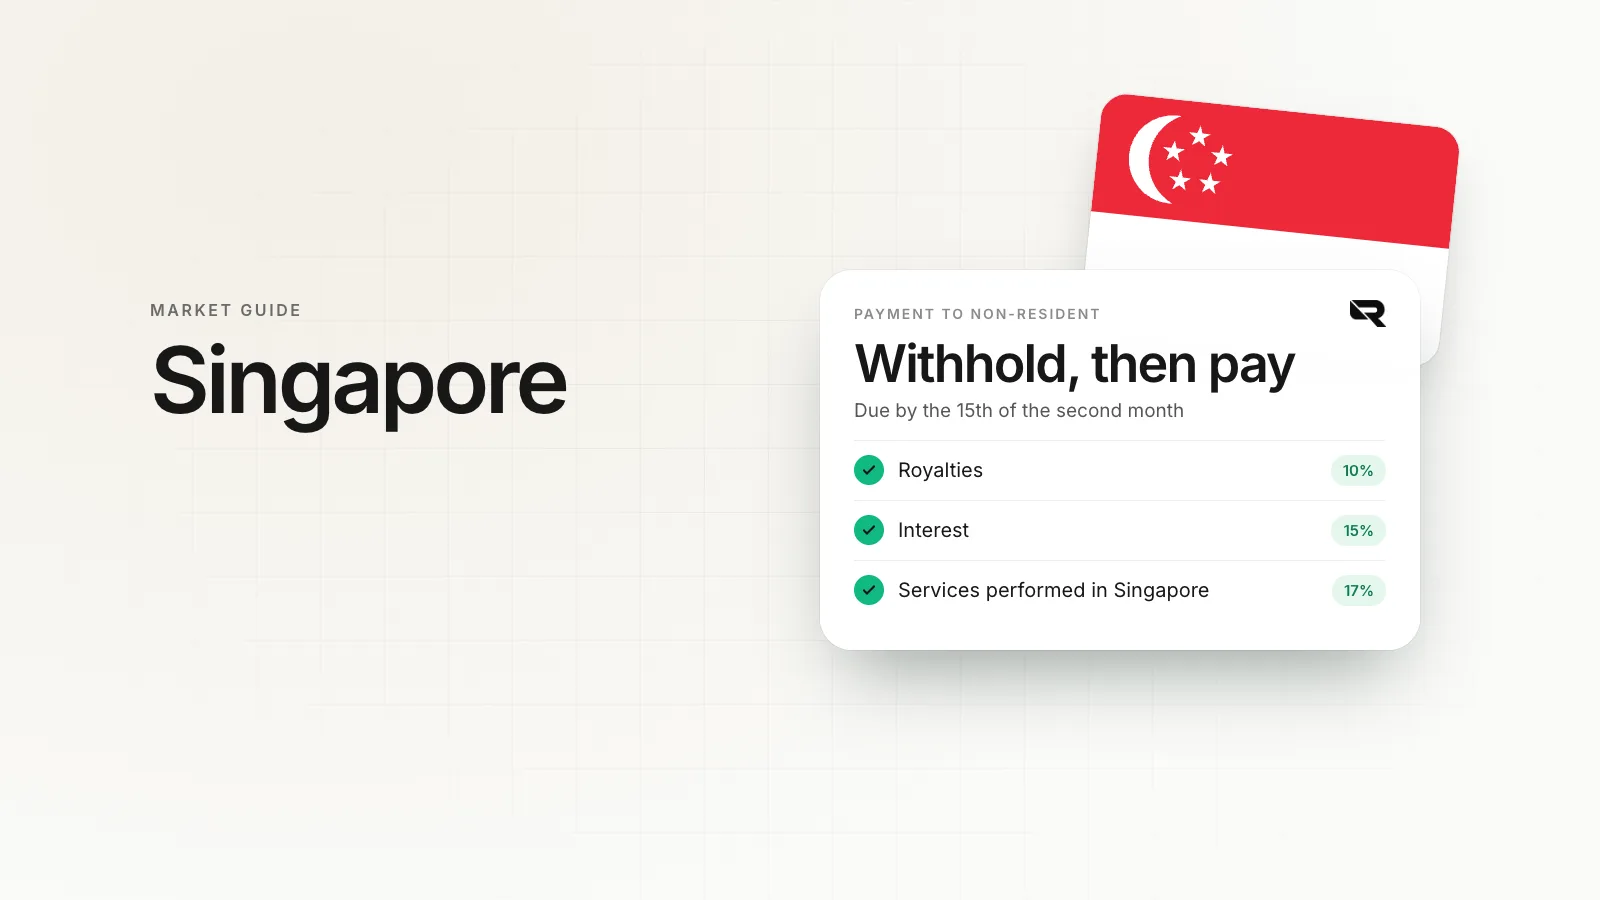
Paying a foreign consultant or licensing software from abroad can trigger Singapore withholding tax. The rate depends on the payment type, and the tax is due by the 15th of the second month after payment.
- Published
- Reading time
- 2 min read
"Payment to overseas supplier withholding tax" appears in Google's suggestions for Singapore searches next to "best way to pay overseas suppliers". The two questions belong together: a Singapore company that pays abroad has to know whether part of the payment belongs to IRAS first.
What is covered
Withholding tax applies to specific payments made to non-residents. The common ones for a small company:
| Payment | Prevailing rate (IRAS) |
|---|---|
| Interest on loans | 15% |
| Royalties, including some software and know-how payments | 10% |
| Services performed in Singapore by a non-resident company | 17% |
| Management fees for work done in Singapore | 17% |
Treaties can reduce these. Services performed entirely outside Singapore are generally outside the rules.
How it works in practice
A Singapore company pays a US consultant S$20,000 for a workshop delivered in Singapore. Unless an exemption or treaty applies, it pays the consultant S$16,600, files a return and sends S$3,400 to IRAS by the 15th of the second month after the payment date. The consultant gets a record of tax withheld.
If the same consultant had delivered the work remotely from the US, withholding would generally not apply.
Set up payments so they are easy to evidence
- Keep the contract, the invoice and where the work was done.
- For royalties and interest, collect a certificate of residence if you apply a treaty rate.
- Pay the supplier and the tax as separate, clearly labelled payments.
Paying into Singapore: the local rail
| What | Detail |
|---|---|
| Local rail | FAST and PayNow |
| Run by | Banking Computer Services, under the Association of Banks in Singapore |
| Settlement | Seconds, 24/7, up to S$200,000 per FAST transfer |
Source: Association of Banks in Singapore: FAST. Checked when this guide was last updated; the scheme's own page has the current figures.
Where Rivet fits
Rivet pays suppliers and contractors in 120+ countries from your company's balance, in their currency on local rails where available, with every payout on one ledger and downloadable receipts. That makes the record of what was paid, when and to whom easy to show IRAS. Check our eligibility list for Singapore companies. Rivet is not a bank; regulated partner institutions hold the funds. See Payouts and how to pay international contractors.
Questions people ask
Do I withhold tax when paying an overseas freelancer?
Generally not, if the work is done entirely outside Singapore. If the freelancer performs the service in Singapore, withholding can apply. IRAS publishes guidance on each payment type.
Does a tax treaty reduce the rate?
Often. Singapore's tax treaties reduce withholding on interest and royalties for residents of treaty countries. The recipient may need to provide a certificate of residence.
Is software a royalty?
It depends on what is licensed. Payments for the right to use software for internal business may be exempt; payments that grant rights to copy or distribute can be royalties. Check IRAS guidance before you pay.
What happens if I forget to withhold?
The payer is liable for the tax and late payment penalties. File and pay as soon as you notice, and keep records of each payment.
Sources
Alexia compares the accounts, cards and payment tools companies weigh before they switch, and writes Rivet's market guides for founders in a specific country. Prices in Alexia's comparisons come from each provider's own pricing page on the date given in the article, rules come from the regulator or tax authority that sets them, and every source is listed at the end.
More from Alexia M. →This article is general information, not legal, tax or financial advice. Rules and fees change; check the sources above and the provider’s current terms before you act on them.
- singapore withholding tax
- iras
- section 45
- non-resident payments