Letters of credit explained for small importers and exporters
A letter of credit is a bank's promise to pay a seller when they prove they shipped. It protects both sides of a trade, for a price. Here is how it works.
- Published
- Reading time
- 2 min read
"Letter of credit meaning" is searched by importers whose supplier just asked for an LC, and by exporters who want to be sure they will be paid. An LC solves a trust problem between two parties in different countries, using banks as the go-between.
What a letter of credit is
A letter of credit is a bank's written promise to pay the seller a set amount, on behalf of the buyer, when the seller presents documents that comply with the LC's terms. Most LCs are issued under the International Chamber of Commerce's UCP 600 rules.
How it works, step by step
- Buyer and seller agree in the sales contract to pay by LC.
- The buyer asks its bank (the issuing bank) to open the LC, listing the documents required.
- The issuing bank sends the LC to the seller's bank (the advising bank), which passes it to the seller.
- The seller ships the goods and collects the documents: commercial invoice, bill of lading, packing list, certificates.
- The seller presents the documents to its bank, which checks them and forwards them.
- If the documents comply, the issuing bank pays. The buyer then receives the documents and collects the goods.
Banks check documents, not goods
The key rule: banks examine documents only. If the invoice describes the goods slightly differently from the LC, or the bill of lading is dated a day late, the bank can refuse to pay, even if the goods are perfect. Most LC problems are document discrepancies, so sellers should check the LC's terms carefully as soon as it arrives.
Types you will see
| Type | Meaning |
|---|---|
| Irrevocable | Cannot be changed without everyone's agreement (the norm under UCP 600) |
| Confirmed | A second bank, usually in the seller's country, adds its own promise to pay |
| At sight | Paid when compliant documents are presented |
| Usance (deferred) | Paid a set number of days after presentation |
Costs
The buyer pays its bank an issuing fee, typically a percentage of the amount, plus amendment and handling fees. The seller may pay advising fees and, for a confirmed LC, a confirmation fee that reflects the risk of the issuing bank and country. Ask both banks for their tariffs before agreeing.
Letter of credit vs line of credit
A letter of credit guarantees payment in a trade. A line of credit is a loan facility. They share a name and nothing else.
When to use one
- Large orders with a new partner
- Countries where enforcing a contract would be slow or uncertain
- When the supplier requires it
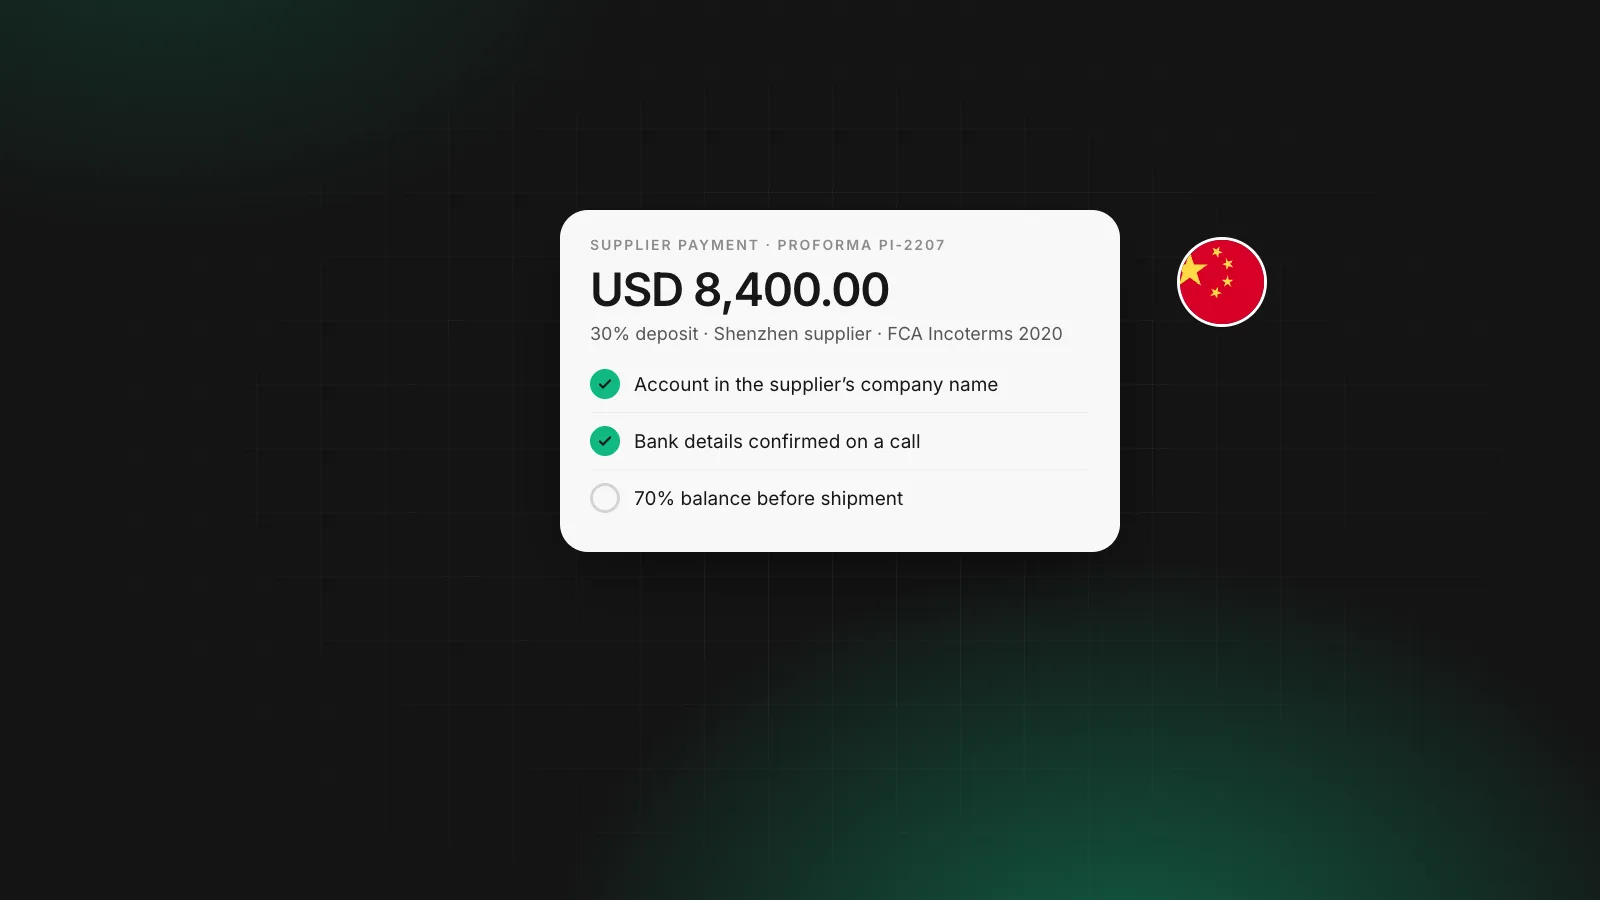
For smaller and repeat orders, a deposit-and-balance bank transfer is usually enough. See how to pay suppliers in China, and Incoterms explained for who is responsible for the goods at each stage.
Where Rivet fits
Rivet does not issue letters of credit; your trade bank does. Rivet handles the everyday payments around trade: receiving from buyers on local rails, paying suppliers abroad, and holding the currencies you trade in. See Payouts.
Questions people ask
What does letter of credit mean?
A written promise from a bank, made on behalf of a buyer, to pay a seller a specified amount when the seller presents documents that comply with the agreed terms, usually showing the goods were shipped.
What is the difference between a letter of credit and a line of credit?
A letter of credit guarantees payment to a seller in a trade, based on documents. A line of credit is a borrowing facility a bank gives a business to draw on as needed. One is a payment instrument; the other is a loan.
How much does a letter of credit cost?
Banks charge the buyer an issuing fee, often a fraction of a percent to a few percent of the amount depending on risk and term, plus fees for amendments and document checking. The seller may pay advising and confirmation fees. Ask both banks for their tariff.
When should a small business use a letter of credit?
For large orders with a new trading partner, in countries where legal recourse would be hard, or when a supplier requires it. For small or repeat orders with a trusted partner, the cost and paperwork usually outweigh the protection.
Sources
Rashidatou writes Rivet's guides to how money moves between countries: the payment rails, what each one costs, and the account details a company needs to get paid in another currency. Every figure in Rashidatou's articles is traced to the scheme rulebook, the regulator or the provider's published price list, and those sources are listed at the end.
More from Rashidatou K. →This article is general information, not legal, tax or financial advice. Rules and fees change; check the sources above and the provider’s current terms before you act on them.
- letter of credit
- letter of credit meaning
- letter of credit vs line of credit
- letter of credit fees
- trade finance