Can you cancel or reverse a wire transfer?
You can cancel a wire until your bank executes it. Once a domestic wire has settled, the sending bank can only ask the receiving bank to return the money, which usually needs the recipient's consent. For fraud, call your bank at once: every hour lowers the chance of recovery.
- Published
- Reading time
- 2 min read
If you have just sent a wire to the wrong account, or to a fraudster, read the first section and then call your bank. The rest can wait.
What should you do in the first hour?
- Call your bank's wire or fraud line, not the general number. Have the amount, date, beneficiary name and account, and any reference ready.
- Ask the bank to cancel the wire if it has not gone, or to send a recall request immediately if it has.
- If it is fraud, ask the bank to contact the receiving bank directly to freeze the funds.
- File a report at the FBI's Internet Crime Complaint Center (ic3.gov).
- Write down every call: time, person, what they said.
Can a wire be cancelled?
Under Article 4A of the Uniform Commercial Code, which governs wires in the US, a sender can cancel a payment order before the bank accepts it, usually by executing it. In practice, that window is between your request and the bank's release. If you scheduled a wire for later in the day, or it needs a second approver in your company, you may still be in time.
What happens after a wire is sent?
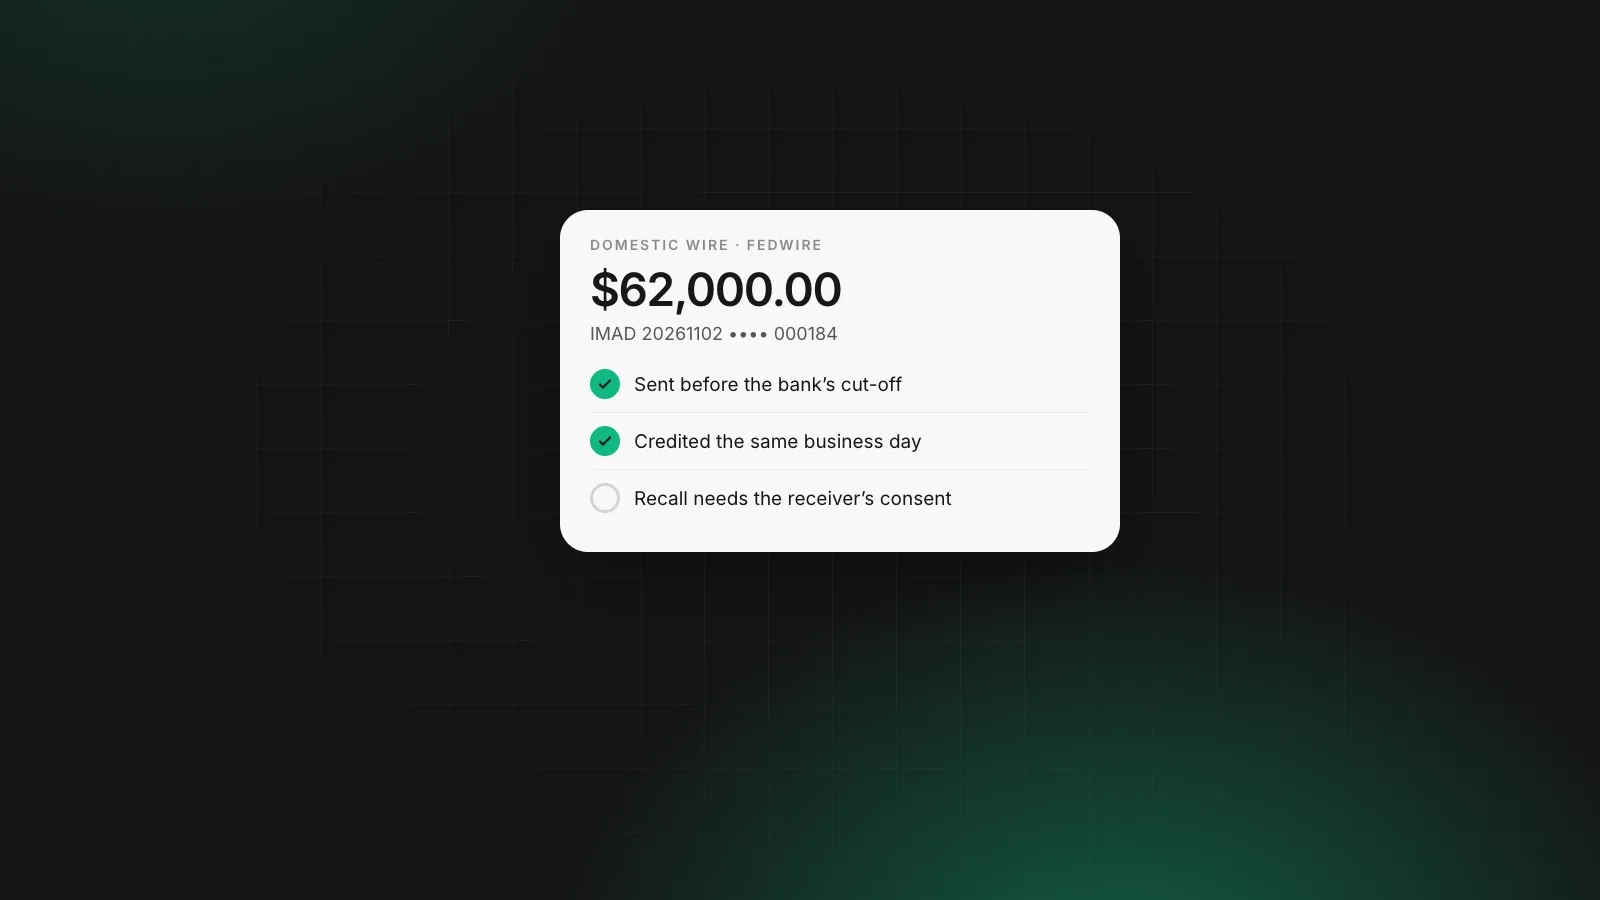
A domestic wire on Fedwire settles in real time and is final. From then on, getting the money back depends on the receiving bank and the recipient. Your bank can send a recall request, and the receiving bank can:
- Return the money if the recipient agrees.
- Freeze the account if it believes the funds are fraudulent.
- Decline, if the recipient refuses and there is no evidence of fraud.
For international wires over SWIFT, banks can send a recall message through each bank in the chain. Each one has to act, so time matters even more.
Are businesses protected like consumers?
Less. Federal rules under Regulation E give consumers sending remittances abroad a 30-minute cancellation right and error resolution rights. Business-to-business wires are not covered by those rules. A business's protection comes from its agreement with its bank, which usually requires security procedures such as call-backs, and from its own controls.
What about wire fraud?
The FBI reports business email compromise as one of the costliest frauds for US companies. The pattern is familiar: an email that looks like it comes from a supplier, a law firm or the CEO, with new bank details and urgency. For international wires, the FBI's Financial Fraud Kill Chain works with banks to try to freeze funds, and it has the best chance when fraud is reported within 72 hours.
Our article on invoice fraud and payment detail scams has a prevention checklist.
How do you prevent the next one?
- Confirm any new or changed bank details by phone, using a number already on file.
- Require two people to approve wires above a set amount.
- Send a small first payment to a new payee and have them confirm receipt.
- Never act on a change of bank details sent only by email.
- Check the beneficiary name matches the company on the contract.
How Rivet helps
From the Growth plan, a Rivet workspace has team roles and approvals, so a payment can need a second person before money moves. Each payout shows the recipient name and details before it is approved, which is the step that stops most payment fraud.
Questions people ask
How long do I have to cancel a wire transfer?
Until your bank sends it. Once it is executed on Fedwire or SWIFT, cancellation becomes a recall request. For consumers sending money abroad, federal rules give a 30-minute window after payment, but that protection does not cover business accounts.
Can my bank force the money back?
Generally no. After settlement the funds belong to the receiving account holder. The receiving bank can freeze or return them if it agrees there was fraud or error, and some will, but it is not automatic.
What if I sent a wire to the wrong account number?
Call your bank with the wire details and ask it to send a recall request. If the account number does not exist, the wire usually comes back by itself. If it went to a real account, the holder has to agree to return it.
What is the Financial Fraud Kill Chain?
A process run by the FBI with banks to try to freeze international wires sent because of fraud. It works best when the fraud is reported within 72 hours, through IC3 and your bank, and is aimed at larger losses.
Sources
Rashidatou writes Rivet's guides to how money moves between countries: the payment rails, what each one costs, and the account details a company needs to get paid in another currency. Every figure in Rashidatou's articles is traced to the scheme rulebook, the regulator or the provider's published price list, and those sources are listed at the end.
More from Rashidatou K. →This article is general information, not legal, tax or financial advice. Rules and fees change; check the sources above and the provider’s current terms before you act on them.
- cancel wire transfer
- wire recall
- wire fraud
- reverse wire
- us payments
- business email compromise