UK corporation tax rate 2026: main rate, small profits and marginal relief
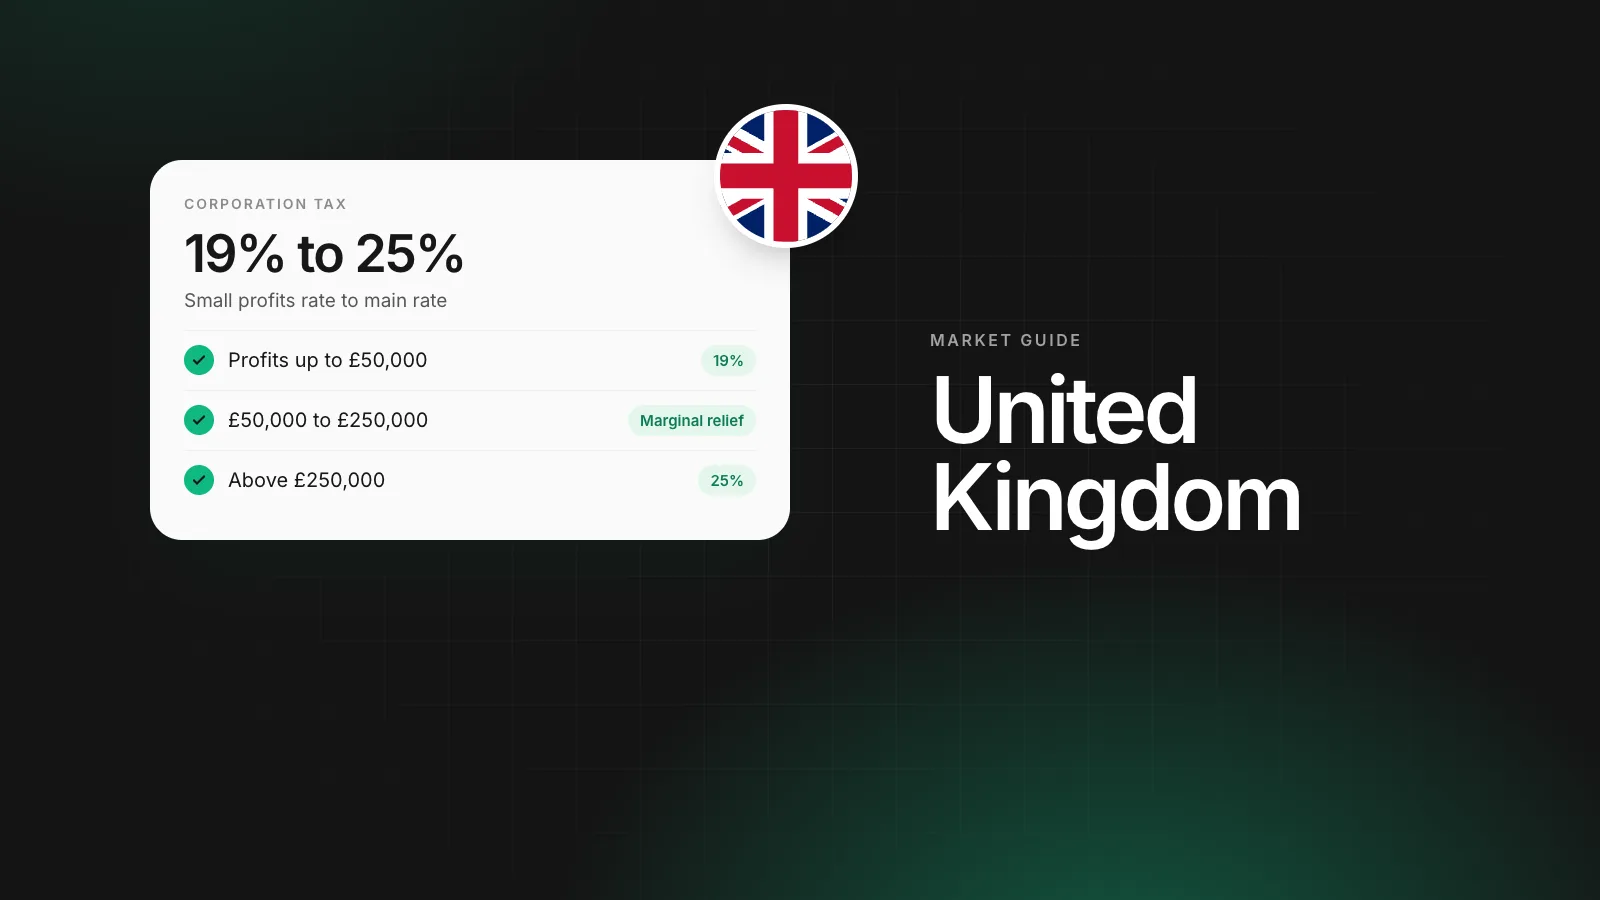
UK companies pay 25% on profits above £250,000 and 19% on profits up to £50,000. Between the two, marginal relief gives an effective rate that rises from 19% to 26.5% on the slice in between.
- Published
- Reading time
- 2 min read
"UK corporate tax rate 2026" sits beside "uk corporate tax rate compared to other countries" in Google's suggestions. The rates have not changed since April 2023, but the band in the middle catches many small companies out.
The rates
| Taxable profits | Rate |
|---|---|
| Up to £50,000 | 19% |
| £50,000 to £250,000 | 25% less marginal relief |
| Above £250,000 | 25% |
Marginal relief worked through
A company with profits of £150,000 and no associated companies:
- Tax at 25%: £37,500.
- Marginal relief: (£250,000 − £150,000) × 3/200 = £1,500.
- Tax due: £36,000, an effective rate of 24%.
The slice between £50,000 and £250,000 is taxed at 26.5% at the margin, which is why timing of income near the thresholds matters.
Associated companies
The £50,000 and £250,000 limits are divided by the number of associated companies. Two companies under common control each have limits of £25,000 and £125,000. Founders with a holding company and a trading company should check this.
Dates
- Payment: nine months and one day after the end of the accounting period, for most companies.
- Return: 12 months after the end of the period.
- Large companies with profits above £1.5 million pay in quarterly instalments.
Currency and the tax bill
Corporation tax is calculated in sterling, but exchange gains and losses on foreign currency balances can count. A UK company holding dollars should keep a clear ledger of conversions so the accountant can compute them.
Paying into the United Kingdom: the local rail
| What | Detail |
|---|---|
| Local rail | Faster Payments |
| Run by | Pay.UK |
| Settlement | Seconds, 24/7; the scheme limit is £1,000,000, and each bank sets its own |
Bacs still carries most payroll and Direct Debits, on a three-day cycle.
Source: Pay.UK: Faster Payment System. Checked when this guide was last updated; the scheme's own page has the current figures.
Where Rivet fits
Rivet records each receipt, conversion and payout with its rate and date, and exports statements that make year-end FX work straightforward. USD details come on the free Starter plan; EUR and GBP on Growth. Rivet is not a bank; regulated partner institutions hold the funds. See salary vs dividends for a UK director.
Questions people ask
What is the UK corporation tax rate in 2026?
25% main rate and 19% small profits rate, with marginal relief between £50,000 and £250,000. These rates have applied since April 2023.
How is marginal relief calculated?
Tax at 25% minus a relief worked out with HMRC's fraction (3/200) on the gap between £250,000 and your profits. HMRC has a calculator.
When is corporation tax due?
For most companies, nine months and one day after the accounting period ends. The return is due 12 months after.
Do foreign exchange gains count?
Yes. Exchange gains and losses on money held in other currencies generally count in taxable profits under the loan relationship rules. Ask your accountant how they apply to you.
Sources
Alexia compares the accounts, cards and payment tools companies weigh before they switch, and writes Rivet's market guides for founders in a specific country. Prices in Alexia's comparisons come from each provider's own pricing page on the date given in the article, rules come from the regulator or tax authority that sets them, and every source is listed at the end.
More from Alexia M. →This article is general information, not legal, tax or financial advice. Rules and fees change; check the sources above and the provider’s current terms before you act on them.
- uk corporate tax rate
- uk corporation tax 2026
- marginal relief
- small profits rate
- hmrc