UK business bank accounts for non-residents: what works in 2026
Forming a UK Ltd from abroad takes a day. Banking it is harder. Here is why, and the routes that work for non-resident directors.
- Published
- Reading time
- 2 min read
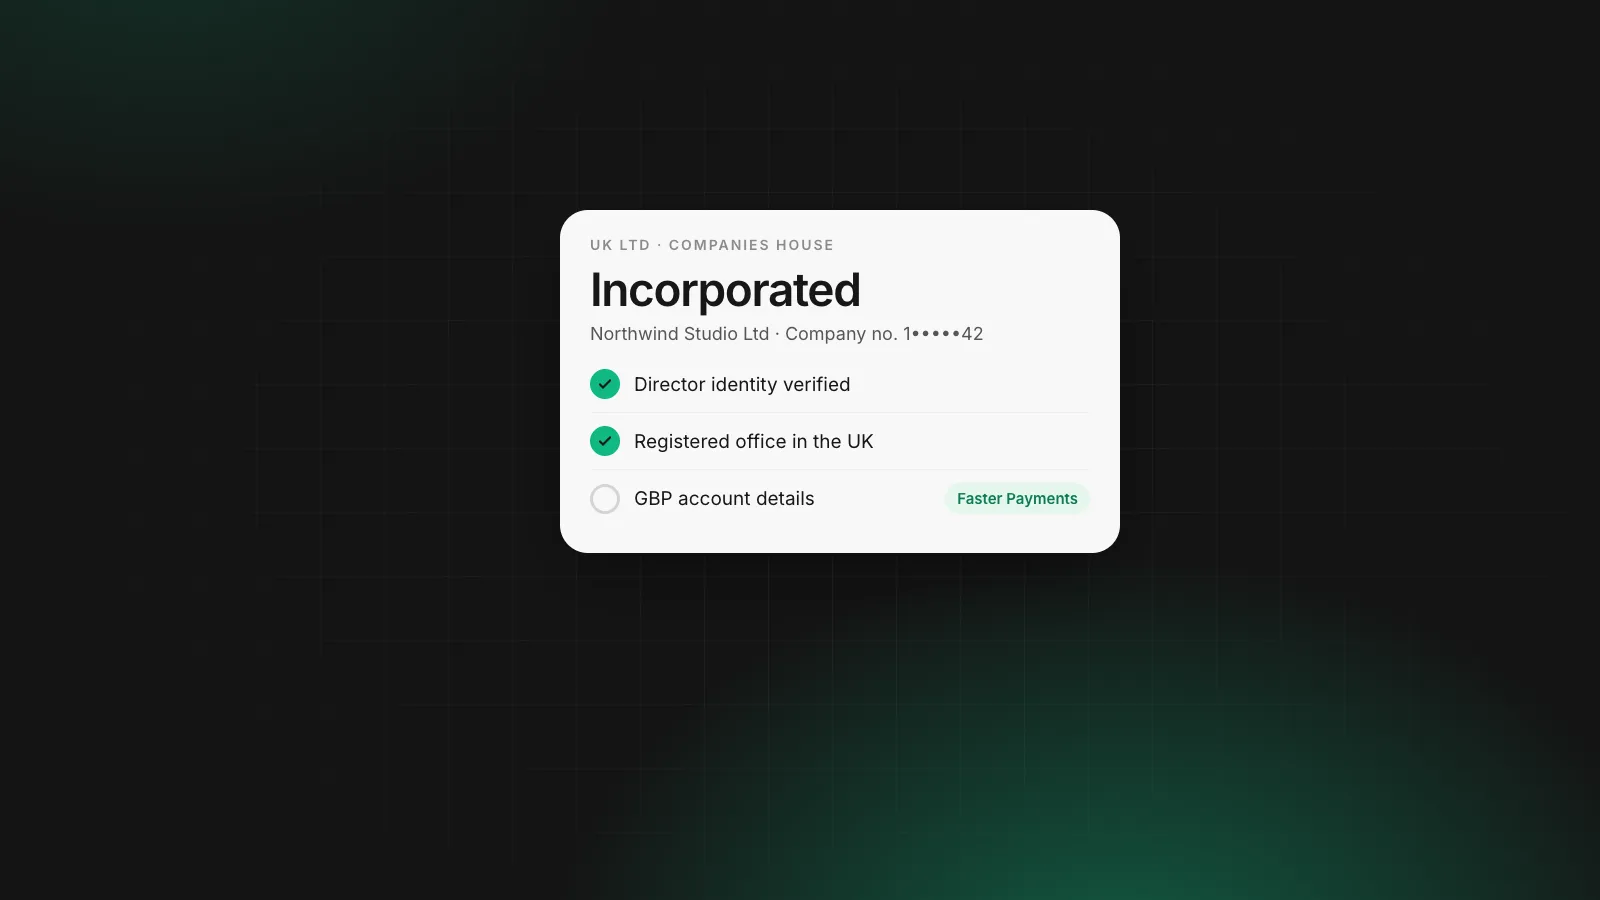
A UK Ltd registered from abroad is a perfectly normal company. Getting it a UK bank account is where many founders stall. "Uk business bank account for non residents" gets searched by founders who have just been turned down by a high-street bank.
Why high-street banks say no
UK banks must verify every director and owner and understand the business. Many high-street banks simplify this by requiring that directors live in the UK, or by asking for a branch visit. A director in Nairobi or São Paulo often fails that test before anyone looks at the business.
The routes that work
| Route | Accepts non-resident directors? | What you get |
|---|---|---|
| High-street bank | Rarely without UK residence | Full bank account, FSCS protection |
| Digital bank | Sometimes; check their country list | Bank account, FSCS protection |
| Payment or e-money institution | Often; each has a country list | GBP details, often multi-currency, safeguarded funds |
Documents to prepare
- Certificate of incorporation and company number
- Register of persons with significant control
- Passport and recent proof of address for each director and each owner of over 25%
- Description of the business: what you sell, to whom, where, and expected monthly volumes
- Website, contracts or invoices that show the business is real
The KYB documents guide explains what each proves.
Bank or payment institution: protection
At a UK bank, the FSCS protects eligible deposits up to 120,000 GBP per depositor per bank. A payment or e-money institution is not covered by the FSCS, but the FCA requires it to safeguard customer money, holding it separately from its own so it is returned to customers if the firm fails. Both are regulated; the protection works differently.
What GBP details give you
A sort code and account number in the company's name. UK clients pay you by Faster Payments, which usually arrives within seconds, at any time. Without them, UK clients pay by international wire, slower and more expensive for everyone.
If you have not formed the company yet
The UK Ltd for non-residents guide covers registration, identity verification and tax residence.
On Rivet
Rivet opens accounts for UK limited companies whose owners live in the countries we support, with no UK residence needed. The Growth plan includes GBP details for Faster Payments alongside USD and EUR, in the company's name. See Bank accounts.
Questions people ask
Can a non-resident open a UK business bank account?
For a UK company, yes, with providers that accept non-resident directors. Many high-street banks do not. Online providers and payment institutions usually verify you remotely, if they accept your country of residence.
What is the best UK business bank account for non-residents?
The one that accepts your country and covers what you need: GBP details for Faster Payments, other currencies if you sell abroad, and cards. Compare eligibility first, then fees.
Is my money protected in an online business account?
At a UK bank, eligible deposits are protected by the Financial Services Compensation Scheme up to 120,000 GBP. At an e-money or payment institution, the FSCS does not apply; instead, the firm must safeguard customer money separately from its own.
Do I need a UK address to open a UK business account?
The company needs a UK registered office. Directors usually do not need a UK home address with online providers, but they need proof of their own residential address wherever they live.
Sources
Rashidatou writes Rivet's guides to how money moves between countries: the payment rails, what each one costs, and the account details a company needs to get paid in another currency. Every figure in Rashidatou's articles is traced to the scheme rulebook, the regulator or the provider's published price list, and those sources are listed at the end.
More from Rashidatou K. →This article is general information, not legal, tax or financial advice. Rules and fees change; check the sources above and the provider’s current terms before you act on them.
- uk company bank account non resident
- uk ltd bank account
- gbp account
- faster payments