What is PAPSS? The Pan-African Payment and Settlement System explained
PAPSS is a payment system that connects central banks, commercial banks and payment providers across Africa, so a payment from Ghana to Nigeria can be sent in cedis and received in naira without first going through US dollars. It launched commercially in 2022 and has been expanding quickly.
- Published
- Reading time
- 2 min read
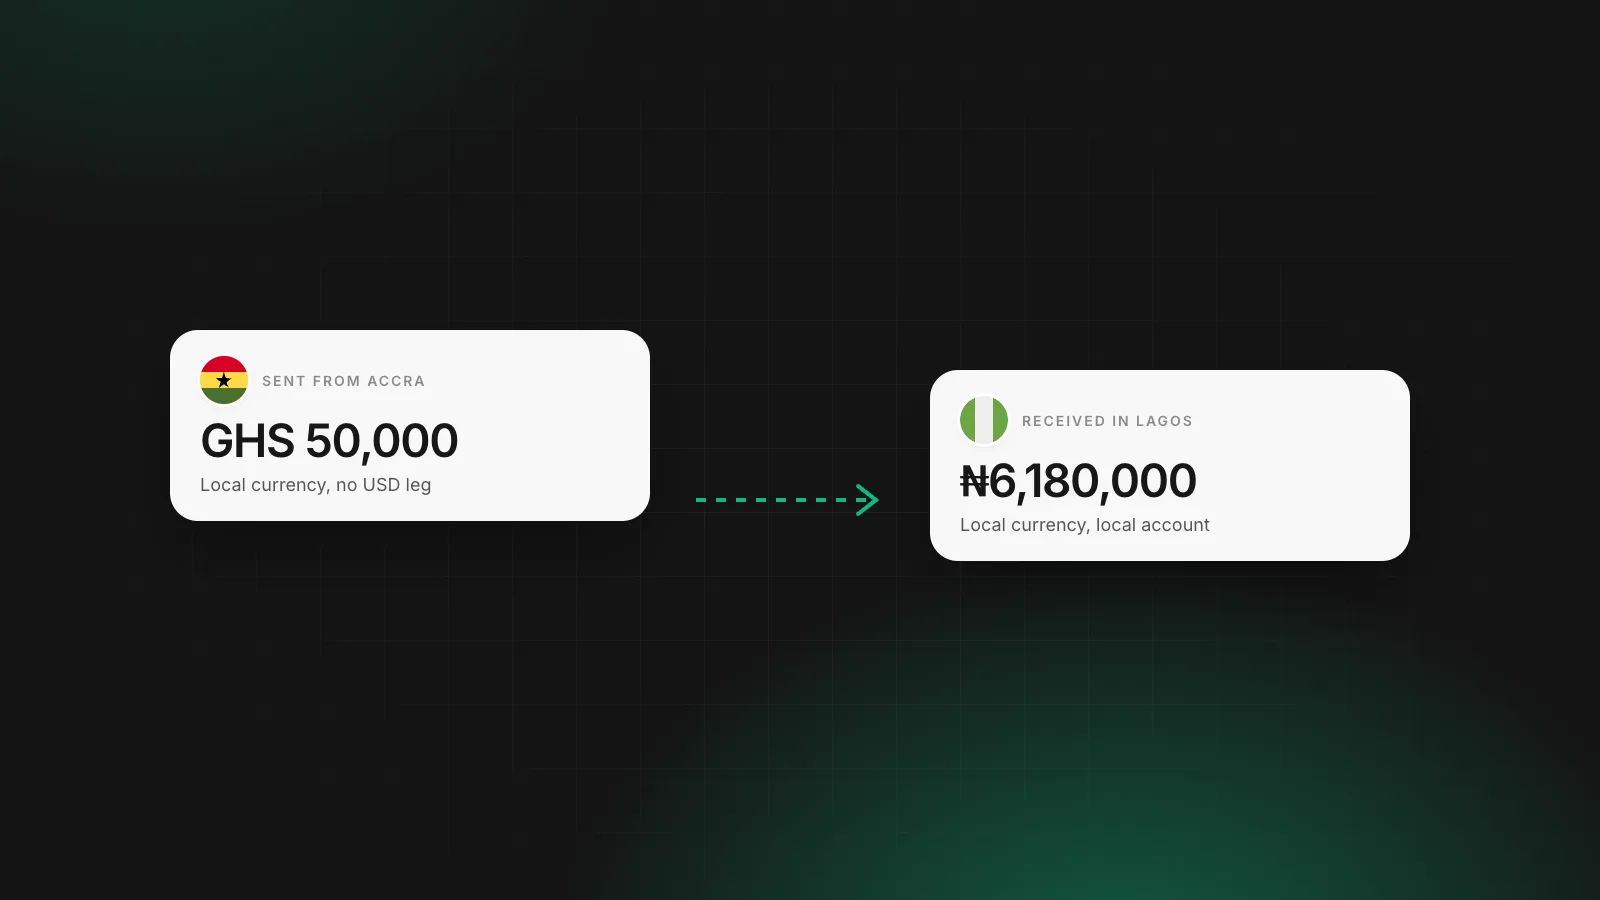
A payment from a buyer in Accra to a supplier in Lagos has traditionally travelled through New York or London. The cedis were converted to dollars, sent through correspondent banks, and converted to naira at the other end. Two conversions, several fees and days of waiting for a payment between neighbours. PAPSS was built to remove that detour.
What is PAPSS?
The Pan-African Payment and Settlement System is a cross-border payment infrastructure developed by the African Export-Import Bank (Afreximbank) with the AfCFTA Secretariat and the African Union. It connects central banks, commercial banks, switches and payment providers in participating countries. It launched commercially in January 2022.
How does a PAPSS payment work?
- A business in Ghana instructs its bank to pay a supplier in Nigeria, in cedis.
- The bank sends the payment through PAPSS.
- PAPSS converts and routes it to the supplier's bank, which credits naira.
- Central banks settle the net positions between countries, with Afreximbank as the settlement agent.
Neither side has to buy US dollars. Payments are designed to complete in seconds to minutes when both banks are connected.
How big is the network?
It has grown quickly. In July 2026, PAPSS said it connected 28 African countries, more than 190 commercial banks and payment firms, and 16 switches. In 2026, the Bank of Central African States (BEAC) joined, with CEMAC banks expected to connect by the end of the year, and Ethiopia's central bank joined in October. Morocco and Algeria also joined in the past two years. PAPSS publishes its coverage on its website.
What else does PAPSS offer?
| Product | What it does |
|---|---|
| PAPSS instant payments | Cross-border transfers between connected banks in local currencies |
| African Currency Marketplace | A platform for exchanging African currencies directly |
| PAPSSCARD | A pan-African card scheme |
What does it mean for businesses?
For a company trading inside Africa, PAPSS can mean:
- Paying suppliers in their currency without holding dollars.
- Fewer conversion losses.
- Faster settlement than SWIFT for intra-African payments.
The limit is adoption. Your bank has to be connected, and so does your counterparty's. Many businesses still find their bank either is not connected or does not yet offer PAPSS to business customers. Ask your bank directly.
How does PAPSS relate to the AfCFTA?
The AfCFTA lowers tariffs on goods traded between African countries. PAPSS lowers the cost of paying for them. Both are meant to make it easier to trade with neighbours than with distant markets. See AfCFTA explained.
When is PAPSS not the answer?
For payments to or from outside Africa, PAPSS does not apply. A Kenyan software company billing a US client still needs USD in, by ACH or wire. Rivet gives registered companies in the countries we support USD account details in their own name for that side, and on Scale holds African currencies, including NGN, KES, GHS, ZAR, XAF and XOF, to convert and pay out.
Questions people ask
How does PAPSS work?
A sender's bank submits the payment in local currency. PAPSS converts it and routes it to the receiving bank in the receiver's currency. Central banks settle the net positions, with Afreximbank as settlement agent.
Can I use PAPSS directly?
Not as an individual or company. You use it through a commercial bank or payment provider that is connected to PAPSS in your country.
Is PAPSS cheaper than SWIFT?
It is designed to be, because it removes the conversion into and out of US dollars and the correspondent banks in between. Actual fees depend on your bank.
Which countries use PAPSS?
The list grows every few months. PAPSS publishes its network coverage. Ghana, Nigeria, Kenya and several West and Central African countries are connected, and the BEAC and Ethiopia joined in 2026.
Sources
Rashidatou writes Rivet's guides to how money moves between countries: the payment rails, what each one costs, and the account details a company needs to get paid in another currency. Every figure in Rashidatou's articles is traced to the scheme rulebook, the regulator or the provider's published price list, and those sources are listed at the end.
More from Rashidatou K. →This article is general information, not legal, tax or financial advice. Rules and fees change; check the sources above and the provider’s current terms before you act on them.
- papss
- pan-african payments
- afreximbank
- afcfta
- cross-border payments africa
- local currency