Thai companies paying foreign service providers: withholding tax (PND 54) and VAT (PP 36)
A Bangkok company paying a Singapore consultancy or a US software vendor usually has two filings to make: withholding tax on the payment, and VAT it self-assesses on the imported service. Both are due within days of the payment.
- Published
- Reading time
- 2 min read
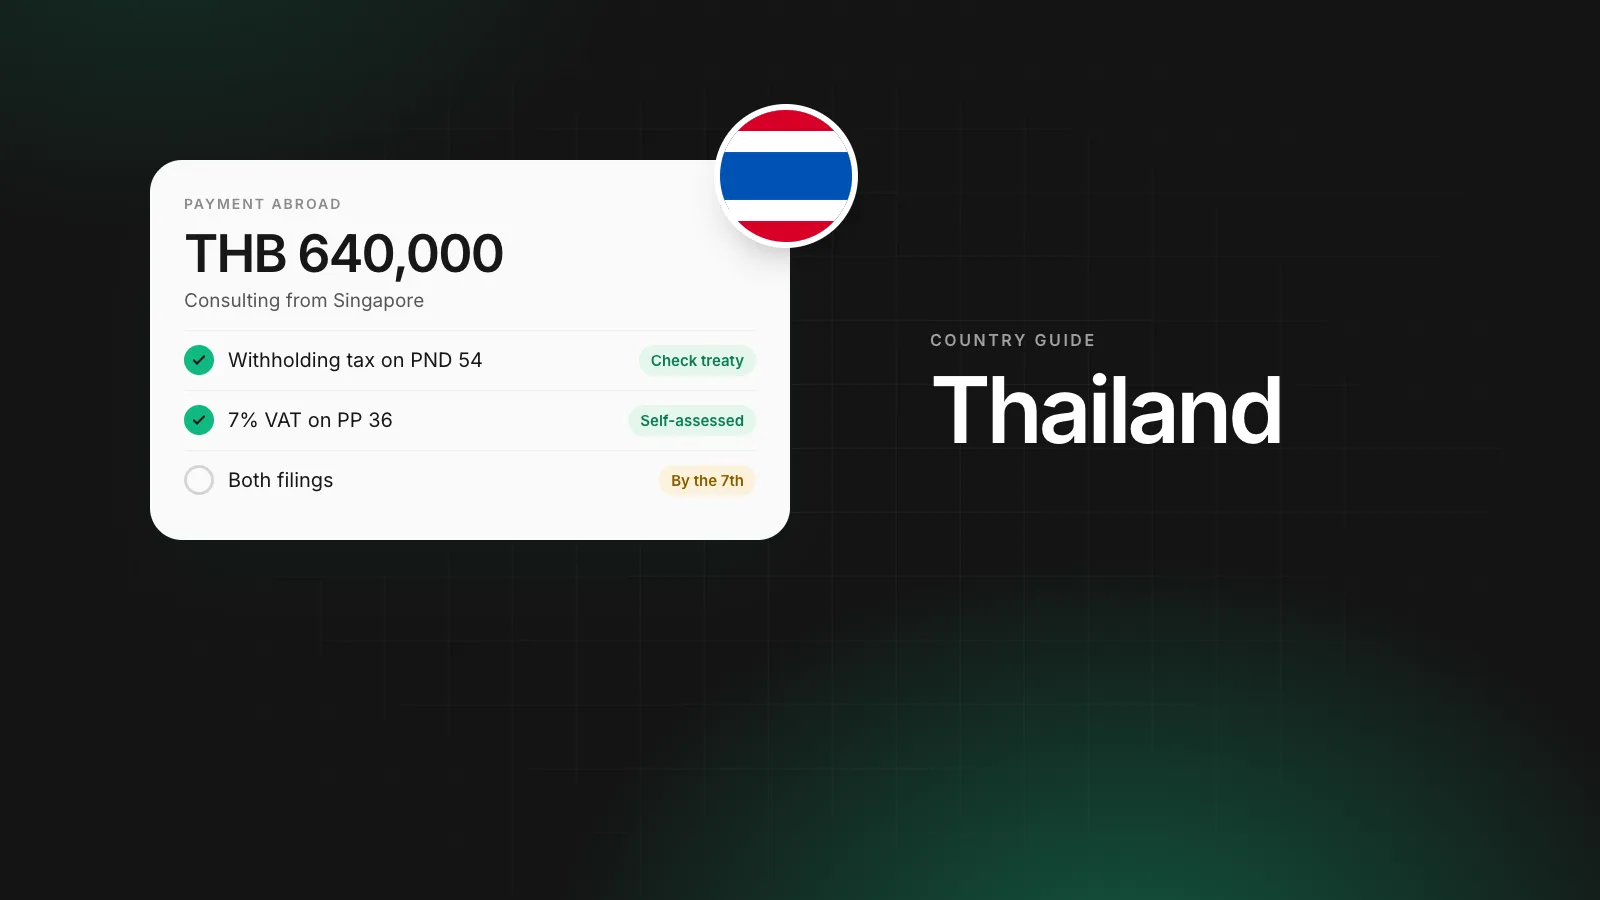
A Bangkok e-commerce company pays a Singapore consultancy THB 640,000 for a supply chain review. Its accountant prepares two filings before the 7th of next month: PND 54, for income tax withheld on the fee or, under the Thailand-Singapore treaty, for none; and PP 36, for the 7 percent VAT the company self-assesses on an imported service.
Withholding tax on PND 54
When a Thai company pays a foreign company that does not carry on business in Thailand for income from Thailand, it generally withholds tax and files PND 54. Common cases:
- service fees,
- royalties for software, trademarks and know-how,
- interest and dividends.
The general rate on service fees to foreign companies is 15 percent. Royalties and interest have their own rates.
Treaties
Thailand has many tax treaties. Service fees are often treated as business profits, taxable only in the provider's country if it has no permanent establishment in Thailand. Royalties are commonly reduced rather than removed. Obtain the provider's certificate of tax residence and keep it on file.
VAT on PP 36
A Thai company buying services from abroad that are used in Thailand self-assesses 7 percent VAT and pays it on PP 36. If the company is VAT registered, it can usually claim the amount as input VAT in the following month's return.
Deadlines
Both PND 54 and PP 36 are due within seven days after the end of the month of payment, with a short extension for e-filing.
Agree gross or net
Foreign providers often quote net. If you gross up, the company bears the withholding on top of the fee. Settle it in the contract.
Paying into Thailand: the local rail
| What | Detail |
|---|---|
| Local rail | PromptPay |
| Run by | National ITMX, under the Bank of Thailand |
| Settlement | Seconds, 24/7 |
Source: Bank of Thailand: PromptPay. Checked when this guide was last updated; the scheme's own page has the current figures.
Where Rivet fits
Rivet does not file Thai taxes. A Rivet business account accepts registered companies after verification, including Thai companies, subject to local rules, and pays providers in 120+ countries with each payment matched to its invoice. Rivet is not a bank; regulated partner institutions hold the funds.
Questions people ask
Which payments to foreign companies require PND 54?
Payments of Thai-source income, such as service fees, royalties, interest and dividends, to foreign companies not carrying on business in Thailand.
Do tax treaties remove withholding on service fees?
Many treaties treat service fees as business profits, taxable only in the provider's country unless it has a permanent establishment in Thailand. Royalties are often reduced rather than removed. Keep the provider's residence certificate.
What is PP 36?
The form a Thai company uses to self-assess and pay VAT on services bought from abroad. The VAT is generally creditable as input tax.
When are these due?
Within seven days after the end of the month in which payment is made, with an extra period for e-filing.
Sources
Rashidatou writes Rivet's guides to how money moves between countries: the payment rails, what each one costs, and the account details a company needs to get paid in another currency. Every figure in Rashidatou's articles is traced to the scheme rulebook, the regulator or the provider's published price list, and those sources are listed at the end.
More from Rashidatou K. →This article is general information, not legal, tax or financial advice. Rules and fees change; check the sources above and the provider’s current terms before you act on them.
- thailand
- withholding tax
- pnd 54
- pp 36
- vat
- foreign providers