The EU AML Regulation from July 2027: what your business will be asked for
From 10 July 2027 one EU regulation replaces 27 national versions of the anti-money laundering rules. For a company that banks or does business in Europe, the checks become more uniform. Here is what to expect.
- Published
- Reading time
- 2 min read
Until now, each EU country wrote its own anti-money laundering law to implement a series of directives. The result was 27 slightly different rulebooks, and a company opening accounts in two countries could be asked for different things. The Anti-Money Laundering Regulation, Regulation (EU) 2024/1624, replaces most of that with one text that applies directly from 10 July 2027.
What is the EU AML Regulation?
It is the core of the EU's 2024 anti-money laundering package. It sets the customer due diligence rules, beneficial ownership rules and reporting duties for banks, payment and e-money firms, crypto-asset service providers and other obliged entities. A separate directive covers national registers and supervisors. A third regulation creates AMLA.
What changes for a company opening an account
The checks themselves will feel familiar. You will still be asked who owns and controls the company, what it does and where its money comes from. What changes is consistency:
- The same core list everywhere. A provider in Ireland and one in Lithuania work from the same text, so their document lists should converge.
- More on ownership chains. Expect questions about each layer of a holding structure until a natural person is reached. Our beneficial owner guide explains how the 25% test works.
- Regular refreshes. Providers must keep customer information up to date, so expect periodic requests for updated documents.
- Crypto in scope. Crypto-asset service providers must run the same checks, and anonymous crypto accounts are prohibited.
The €10,000 cash cap
Businesses that sell goods or services may not accept or make cash payments of €10,000 or more, in one payment or in linked ones. Member states can set a lower cap, and several already have. For most companies working across borders this changes nothing, because they rarely use cash at that size.
What AMLA does
AMLA is based in Frankfurt. From 2028 it will directly supervise a group of large financial firms that operate in several member states and carry high risk. It will also write technical standards that fill in the detail of the regulation, so some specifics will arrive between now and July 2027.
How to prepare
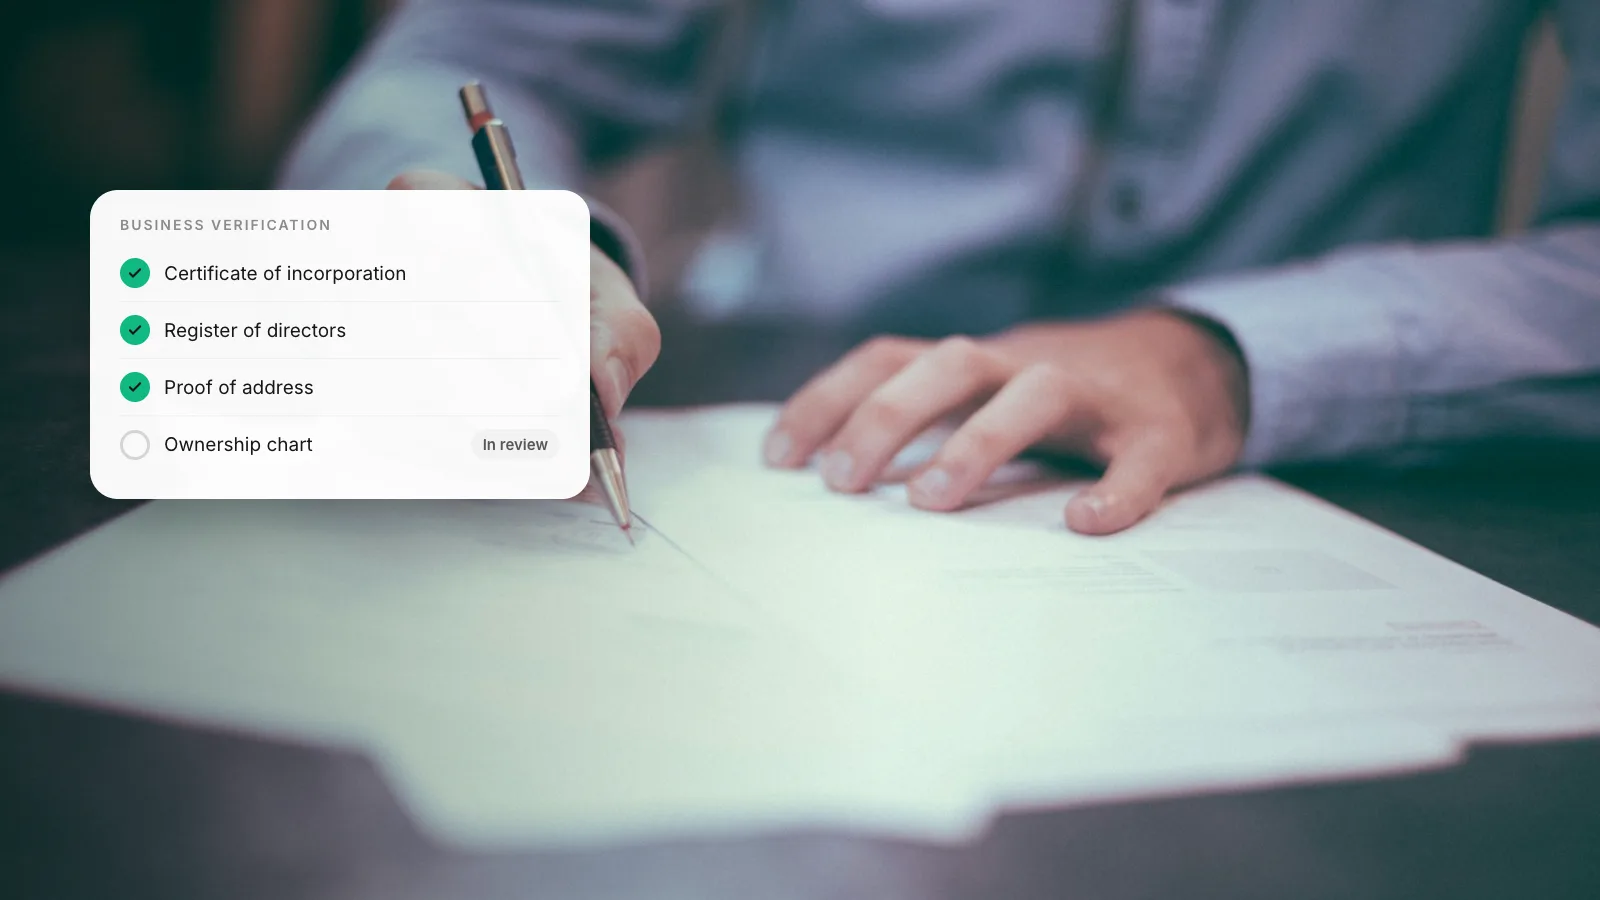
- Keep an ownership chart that runs to every natural person with 25% or more, and anyone who controls the company by other means.
- Keep formation documents, registers and proof of address current. See proof of address for a business account.
- Write a short description of your business model, your main customers and your main payment flows. Reviewers ask for this more and more often.
- Answer refresh requests quickly. Late answers are a common reason accounts get restricted, as our account closures article explains.
Verification on Rivet
Rivet verifies every company before opening accounts and keeps the document list in one place in the dashboard. See Bank accounts for what we ask for.
Questions people ask
When does the EU AML Regulation apply?
From 10 July 2027. It was adopted in 2024 as part of a package with a new directive and the regulation creating AMLA. Because it is a regulation, it applies directly without each country writing its own version.
What is AMLA?
The Authority for Anti-Money Laundering and Countering the Financing of Terrorism, an EU agency based in Frankfurt. It will directly supervise a group of large or high-risk financial firms from 2028 and coordinate national supervisors.
Does the AMLR change who counts as a beneficial owner?
The threshold stays at 25% or more of shares, voting rights or other ownership interest. The regulation adds more detail on control through other means and on layered structures, so expect more questions about how ownership runs through holding companies.
Does the AMLR apply to non-EU companies?
It applies to obliged entities such as banks, payment firms and crypto-asset service providers in the EU. A non-EU company meets it as a customer when it opens or uses an account with one of them.
Sources
William covers what happens once a company starts moving money: getting the business verified, paying contractors and suppliers abroad, and keeping card spend under control. William writes for the founder or finance lead who has to make it work this week, and links every rule cited to the text it comes from.
More from William Sunjo M. →This article is general information, not legal, tax or financial advice. Rules and fees change; check the sources above and the provider’s current terms before you act on them.
- amlr
- eu aml regulation
- amla
- kyb europe
- aml 2027