Ugandan companies paying foreign service providers: withholding tax and VAT on imported services
When a Kampala company pays a Kenyan consultancy or a US software vendor, Uganda's tax law often expects it to withhold tax and to account for VAT on the imported service itself. Both are due soon after payment, and the Uganda Revenue Authority checks.
- Published
- Reading time
- 1 min read
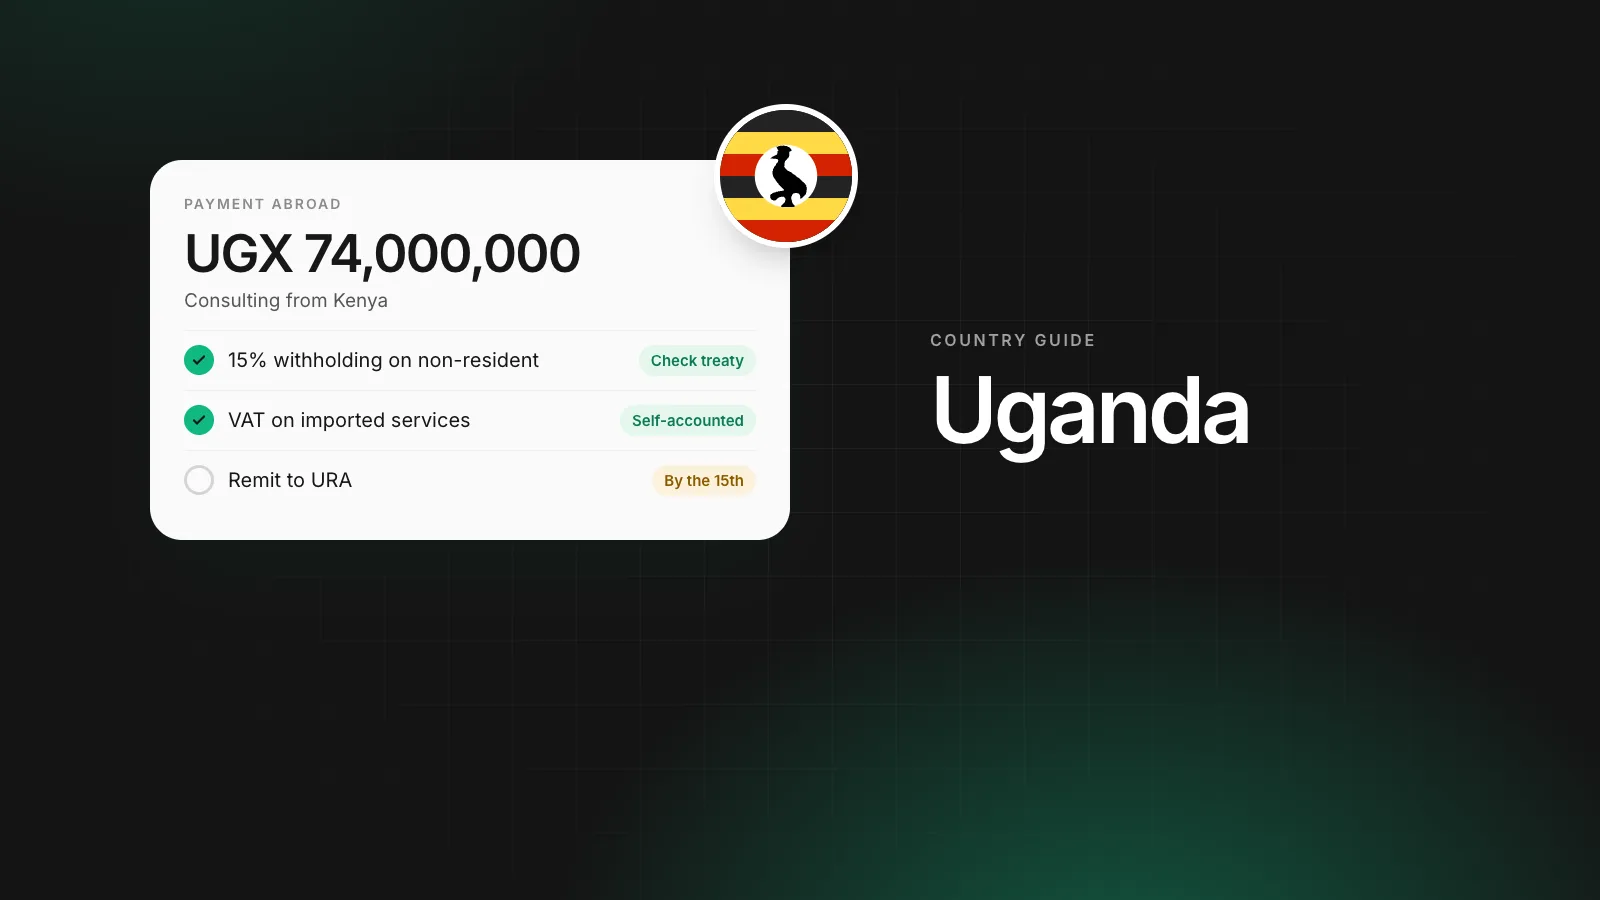
A Kampala telecom services company pays a Nairobi consultancy UGX 74 million for a network study. Its accountant withholds 15 percent on the fee as a payment to a non-resident, unless a treaty changes it, and accounts for VAT on the imported service under the reverse charge. Both go to the Uganda Revenue Authority by the 15th of next month.
Withholding on non-residents
Uganda's Income Tax Act requires withholding, generally at 15 percent, on many payments from Ugandan sources to non-residents, including:
- management and professional fees,
- royalties,
- dividends and interest.
The payer withholds and remits the tax. Failure makes the payer liable.
VAT on imported services
When a Ugandan company receives services from a non-resident, it generally accounts for VAT on the imported service under the reverse charge. Registered companies can usually recover it as input tax if they use the service for taxable supplies.
Treaties
Uganda has a limited network of tax treaties, including some regional ones. Where a treaty applies, the rate may fall. Keep the provider's certificate of tax residence.
Deadlines
Withholding and VAT on imported services are generally due by the 15th of the month after payment.
Gross or net
Foreign providers often quote net. If you gross up, the 15 percent is on top. Agree it in the contract.
Where Rivet fits
Rivet does not file Ugandan taxes. A Rivet business account accepts registered companies after verification, including Ugandan companies, and pays providers in 120+ countries with each payment matched to its invoice. Rivet is not a bank; regulated partner institutions hold the funds.
Questions people ask
What is the withholding rate on payments to non-residents in Uganda?
Generally 15 percent on payments such as management and professional fees, royalties and dividends from Ugandan sources, subject to treaties.
What is VAT on imported services?
A reverse charge where the Ugandan recipient accounts for VAT on services supplied by a non-resident.
When are these due?
Generally by the 15th day of the month following payment.
Do treaties reduce the rate?
Uganda has treaties with some countries that can reduce withholding. Check the relevant treaty and keep the provider's residence certificate.
Sources
William covers what happens once a company starts moving money: getting the business verified, paying contractors and suppliers abroad, and keeping card spend under control. William writes for the founder or finance lead who has to make it work this week, and links every rule cited to the text it comes from.
More from William Sunjo M. →This article is general information, not legal, tax or financial advice. Rules and fees change; check the sources above and the provider’s current terms before you act on them.
- uganda
- withholding tax
- vat
- imported services
- ura
- tax treaties