Omani companies paying foreign providers: the 10 percent withholding tax
When an Omani company pays a foreign firm for royalties, management fees or certain other services, it may have to withhold 10 percent and pay it to the Tax Authority. The payer carries the obligation, and the deadline is short.
- Published
- Reading time
- 1 min read
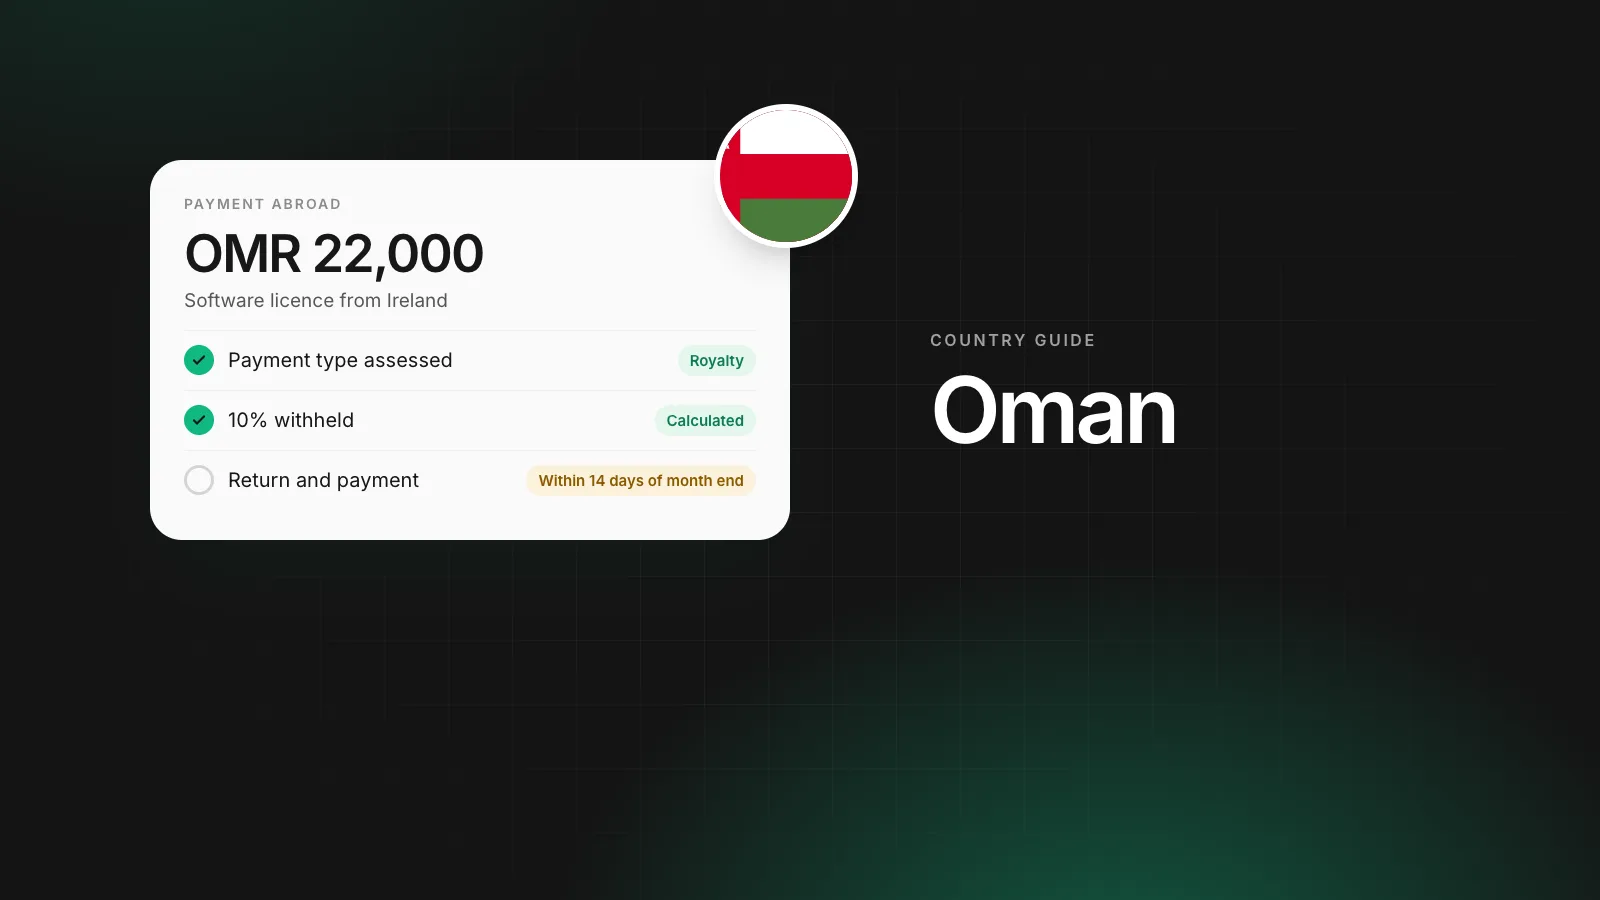
A Muscat logistics company licenses fleet management software from an Irish vendor for OMR 22,000 a year. The vendor has no office in Oman. The payment counts as consideration for the use of computer software, so the Omani company withholds 10 percent, files the return and pays the Tax Authority within 14 days after the month ends.
The withholding rule
Oman's income tax law requires withholding at 10 percent on certain payments to foreign companies that have no permanent establishment in Oman, or whose income is not connected to one. Covered payments include:
- royalties,
- consideration for research and development,
- consideration for the use or right to use computer software,
- management fees,
- and other categories the law adds, such as dividends and interest under specific rules.
Filing
The payer withholds the tax from the gross payment, files the return and pays the Tax Authority within 14 days after the end of the month of payment. The payer is responsible if the tax is not withheld.
Treaties
Oman has double taxation agreements that can reduce withholding. Obtain the provider's certificate of tax residence and follow the Tax Authority's procedure.
Contracts
Foreign vendors often quote net of withholding. If the Omani company agrees to gross up, it bears the 10 percent on top. Settle this in the contract.
Where Rivet fits
Rivet does not file Omani withholding tax. A Rivet business account accepts registered companies after verification, including Omani companies, subject to local rules, and pays providers in 120+ countries with each payment matched to its invoice. Rivet is not a bank; regulated partner institutions hold the funds.
Questions people ask
Which payments carry withholding tax in Oman?
Royalties, consideration for research and development, use or right to use computer software, management fees, and other categories listed in the income tax law, including dividends and interest under rules introduced over time.
What is the rate?
10 percent on the gross amount, subject to treaty relief.
When must the tax be paid?
Within 14 days after the end of the month in which the payment was made or credited.
How do I apply treaty relief?
Obtain the provider's tax residence certificate and follow the Tax Authority's procedure for applying treaty rates.
Sources
Rashidatou writes Rivet's guides to how money moves between countries: the payment rails, what each one costs, and the account details a company needs to get paid in another currency. Every figure in Rashidatou's articles is traced to the scheme rulebook, the regulator or the provider's published price list, and those sources are listed at the end.
More from Rashidatou K. →This article is general information, not legal, tax or financial advice. Rules and fees change; check the sources above and the provider’s current terms before you act on them.
- oman
- withholding tax
- foreign providers
- royalties
- management fees
- tax treaties